Bone Health and Collagen Drive China's Supplement Boom
 By Quan Wenjun
6 min read
Newer data: Sleep, Brain, Anemia: China's Supplement Growth Goes Specialist
Executive Summary#
China's online health supplements market reached CN¥ 115.45 billion in combined sales across three leading Chinese marketplaces in 2023 (+24.6% YoY), and its sub-segments moved in very different directions, which shows where the opportunities for brands lay in 2023. On two leading Chinese marketplaces, bone health grew 34.5% YoY to CN¥ 9.09 billion, helped by youth height-growth products and lysine-based formulations, while oral beauty came under pressure even as its collagen sub-category grew 27.5% to CN¥ 3.13 billion. For brands and investors looking at China's supplement market, we believe these segments show how ingredient innovation, products aimed at particular age groups and changes in regulation are changing the way brands compete.
Bone Health: The Segment That Keeps Accelerating#
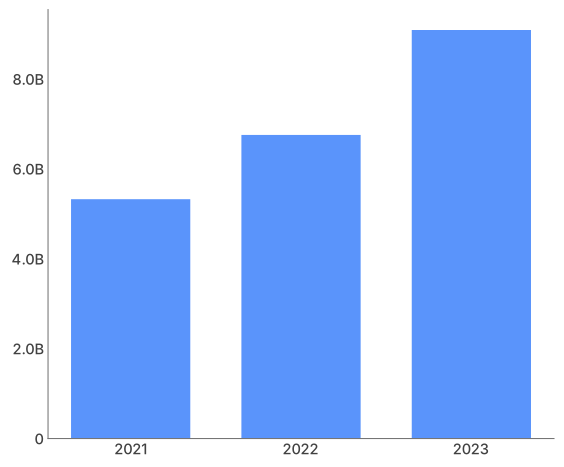
Bone health has grown well beyond its traditional base in calcium. The segment reached CN¥ 9.09 billion on two leading Chinese marketplaces in 2023. What makes its 34.5% YoY growth notable is that it has accelerated: growth rose from 17.2% in 2021 to 26.9% in 2022 and then 34.5% in 2023, whereas categories usually slow down as they grow larger.
Two sources of demand explain this. The first is youth height-growth products, a premium sub-category that barely existed three years ago. Parents who want supplements for their children's growth have taken to lysine-based formulations, which have lifted the CN¥ 500+ price tier from 10.2% to 27.9% of segment sales. Hamiher, allnature and Aismun (爱司盟) are among the brands selling in this premium tier. The second is cross-border sales, which more than doubled from CN¥ 2.02 billion in 2021 to CN¥ 4.22 billion in 2023, as consumers turned to US-origin products, whose share of the segment rose from 21.0% to 34.3%.
Consumer reviews on one of these marketplaces show that demand comes from two distinct groups. Children and adolescents account for 53.5% of demographic mentions in bone health reviews, and middle-aged and elderly consumers for 34.5%. Calcium supplementation (30.5% of scenario mentions) remains the basic need across all age groups, while joint and knee pain (21.6%) and growing taller (11.6%) show how far the segment's functions have widened.
The ingredient data shows the largest change. Calcium remains the base of the segment at CN¥ 6.86 billion, but the fastest-growing ingredients are changing the category: lysine sales reached CN¥ 2.28 billion with growth of 278.3% YoY, which makes it the second-largest ingredient by sales. Hydrolyzed egg yolk powder was also among the fastest-growing ingredients, in products that combine it with GABA and are marketed for adolescent sleep and height growth. Vitamin K grew 134.8% YoY as consumers learned more about the role it is marketed for, directing calcium to bones. We believe the move from simple single-ingredient calcium tablets toward multi-ingredient formulations shows that the segment is maturing.
Bone health market accelerates to +34.5% YoY growth in 2023
Oral Beauty: Consumers Move Toward Evidence-Based Products#
Oral beauty, a CN¥ 9.75 billion segment in 2023, came under pressure over the year. Consumer fatigue with beauty supplements that offer little to tell them apart, tighter regulatory scrutiny of health claims and scattered negative publicity about adverse reactions all weighed on the segment.
Within the segment, domestic Chinese brands gained ground quickly, as the share of Mainland China-origin products rose by 10.6 percentage points to 26.6% in 2023, while the share of US-origin products was 33.0%, against 47.4% the year before. Sales through domestic trade channels reached CN¥ 4.85 billion. Brands such as Five Female PhDs (五个女博士) are building credibility through transparent ingredient sourcing and evidence of efficacy.
We believe consumers are staying with oral beauty. They are concentrating their purchases on products with stronger evidence and clearer information about ingredients, increasingly from domestic brands that compete on innovation more than on the prestige of their country of origin. Japan-origin products held 7.8% of the segment in 2023, against 11.5% in 2021, while New Zealand-origin products rose from 5.1% to 7.5%, helped by the country's reputation for clean ingredients.
Collagen Deep Dive: PQQ, Innovation Ingredients, and Premiumization#
Collagen has gained most from consumers' move toward quality in oral beauty. The sub-segment reached CN¥ 3.13 billion in 2023 (+27.5% YoY), and its share of oral beauty rose from 20.9% in 2021 to 32.1% in 2023. Mainland China-origin products held 55.8% of collagen sales, and domestic trade channels accounted for CN¥ 2.66 billion of the total.
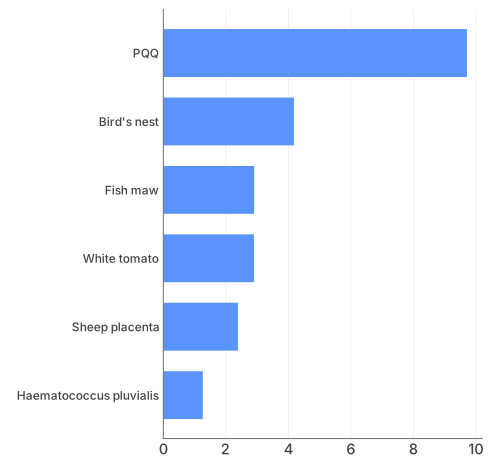
Among new ingredients, PQQ (pyrroloquinoline quinone disodium salt) has become the largest supplementary ingredient in collagen formulations, with CN¥ 970 million in sales (+74.8% YoY). It was helped by China's National Health Commission, which approved PQQ as a new food ingredient in October 2023 and so removed a barrier to product formulation and marketing claims. White tomato, promoted for inhibiting melanin and brightening skin, grew faster still at +80.3% YoY, while bird's nest held CN¥ 418 million in sales by combining the appeal of a traditional Chinese luxury with modern collagen science.
Premiumization runs through the collagen segment. Sales in the CN¥ 600-900 price range grew 112.4% YoY and in the CN¥ 900-1,200 range 110.7%, as more consumers buy in courses that commit them to several months of supplementation. Popular brands in the mid-range CN¥ 300-600 tier include Filide (斐利德), Five Female PhDs, Swisse and By-Health (汤臣倍健). The CN¥ 1,200+ tier came under pressure, which suggests that consumers will not pay the highest prices for products without clear differentiation. Consumer motivations are closely tied to lifestyle, since sleep concerns and staying up late together account for 62.3% of collagen consumption scenario mentions in reviews on one of these marketplaces. This links beauty with wellness positioning and opens formulation opportunities for products that combine collagen with sleep-quality ingredients such as GABA or magnesium.
PQQ leads collagen supplementary ingredients at CN¥ 970 million
Key Takeaways#
- Bone health is a standout growth segment. At CN¥ 9.09 billion (+34.5% YoY) on two leading Chinese marketplaces, with growth that has accelerated for three years, it combines market scale with momentum.
- Youth height-growth products are reshaping the bone health category. Lysine (+278.3% YoY) and hydrolyzed egg yolk powder are driving premiumization, and the CN¥ 500+ price tier nearly tripled its share to 27.9%.
- Oral beauty consumers are moving toward evidence-based products. Collagen grew 27.5% and reached 32.1% of the segment, as consumers concentrate their spending on products with stronger evidence.
- PQQ is the ingredient to watch in collagen. After its regulatory approval in October 2023, it reached CN¥ 970 million in sales (+74.8% YoY) and is the largest supplementary ingredient in collagen formulations.
- Domestic brands are gaining ground in oral beauty. Chinese-origin oral beauty products gained 10.6 percentage points of share in a single year, while the share of US-origin products fell 14.4 points. We believe this reflects a structural shift toward local innovation.
About the Data#
This analysis is based on Moojing Market Intelligence data covering three leading Chinese marketplaces for the period Q2 2024; the segment, ingredient, price-tier, origin and review figures are from two of them.
Download the Full Report#
More from This Report#
This content adheres to Moojing's editorial standards .


