China's Online Home Appliance Sales Hit CN¥ 766B in 2025
 By Jotham Lim
4 min read
Executive Summary#
China's online home appliance market reached CN¥ 766.35 billion in 2025, growing 18.1% year on year while volume rose 46.8% to 1.71 billion units. The national trade-in subsidy programme lifted sales, and the categories it touched moved in very different directions. Large home appliances held 60% of the market at CN¥ 459.4 billion.
Download Full Report#
Get the complete analysis with additional data, methodology details, and brand-level insights.
Subsidy-Driven Growth Faces Structural Divergence#
China's national home appliance trade-in subsidy, which began in 2024, has been the defining force in the appliance market[1]. The programme lifted consumption across most categories, but its effect weakened in late 2025 as pent-up demand was absorbed. The renewed policy that the National Development and Reform Commission and the Ministry of Finance announced in December 2025 covers fewer categories and offers smaller incentives, so 2026 will show how much of the growth the market can sustain without continued government support.
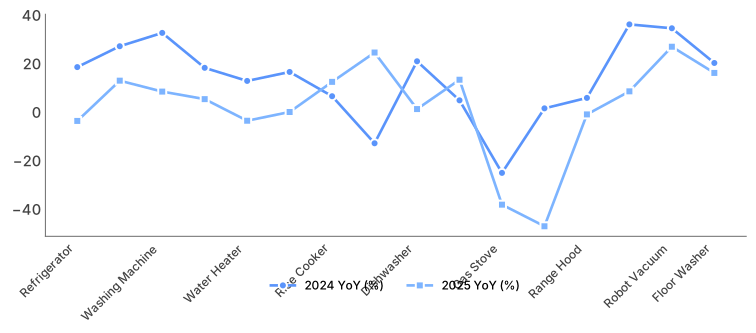
The divergence between categories points to structural changes that go beyond the subsidy. Cleaning appliances kept growing strongly as lifestyle purchases, while traditional kitchen products contracted as replacement cycles were completed and cooking habits changed. Robot vacuums grew 27.0% and floor washers 16.2%, while gas stoves fell 38.1% and disinfection cabinets 47.0%.
Key trends during the subsidy period:
- Electric ovens reversed their 2024 decline, moving from -12.8% to +24.6% as the subsidy released latent demand
- Refrigerators turned negative, moving from 18.6% growth to a decline of 3.6%, which suggests that the subsidy pulled replacement demand forward
Trade-in subsidy effect diverges sharply across appliance categories in 2025
Market Size: CN¥ 766.35 Billion Across Four Segments#
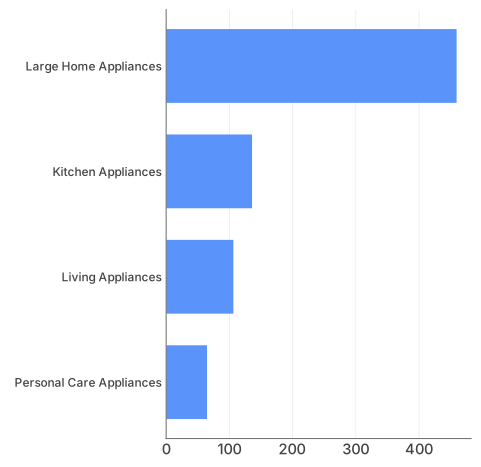
China's online home appliance market reached CN¥ 766.35 billion in total sales value and 1.71 billion units sold in 2025[3]. Revenue grew 18.1% while volume grew 46.8%, so the market expanded mainly through the number of units sold, and average selling prices moved down over the period.
Large home appliances, which include air conditioners, refrigerators, washing machines and televisions, held 59.9% of the market at CN¥ 459.4 billion. Personal care appliances were the smallest of the four segments, at CN¥ 64.7 billion.
Large home appliances hold 60% of online home appliance sales across four segments
Major Appliance Performance: Air Conditioners Lead, Refrigerators Reverse#
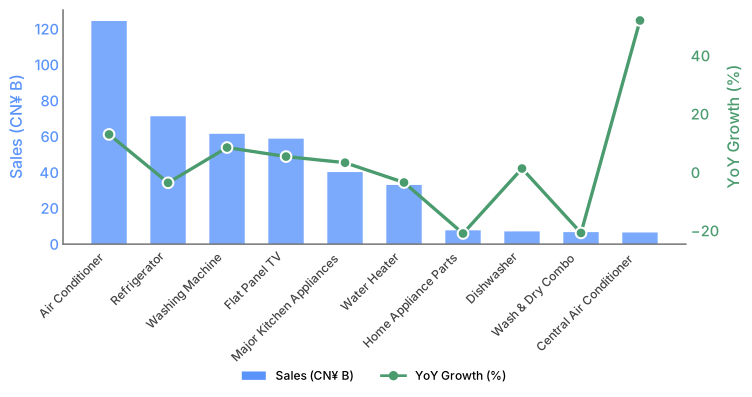
Air conditioners were the largest major appliance category at CN¥ 124.4 billion and grew 13.0%. Central air conditioners grew fastest in the segment at 52.1%, which reflects a move towards whole-home climate systems in premium renovations.
Refrigerators declined 3.6% after growing 18.6% in 2024, which suggests that much of the subsidy-driven demand was pulled forward. Washing machines grew more steadily at 8.5%, which points to continued demand for smart-connected and larger-capacity models. Sales of home appliance parts fell 21.0% and wash-dry combos 20.8%.
Central air conditioners grow 52.1% while appliance parts and wash-dry combos decline
Living Appliance Performance: Robot Vacuums and Floor Washers Reshape Cleaning#
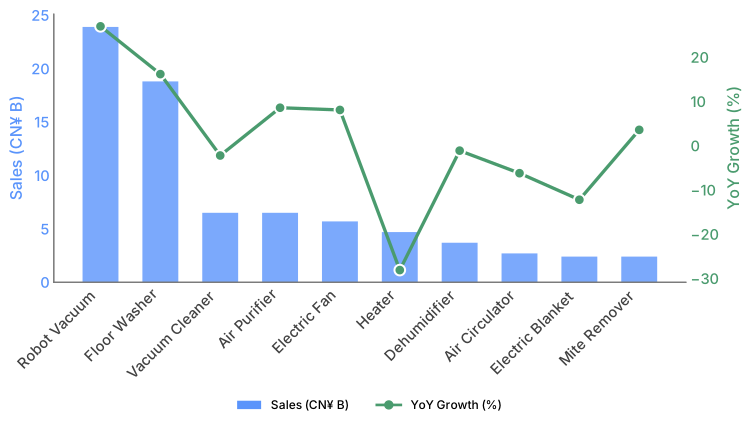
Robot vacuums and floor washers together accounted for CN¥ 42.7 billion, or 40.2% of the living appliance segment, and grew 27.0% and 16.2% respectively. Through innovations such as self-emptying stations, built-in mopping and AI-powered obstacle avoidance, the two categories have changed how households clean. They are taking the place of traditional vacuum cleaners, whose sales fell 2.2%.
Heaters had the largest decline in the segment at 28.1%, which we believe reflects a mild winter and a preference for central heating and air conditioning. Air purifiers grew 8.6%, which suggests that consumers' attention to health keeps demand going whatever the season. Within living appliances, sales are moving from passive comfort products towards active, technology-led products.
Robot vacuums and floor washers drive cleaning appliance growth above 16%
About the Data#
This analysis draws on Moojing Market Intelligence data covering January-December 2025[3]. Moojing analyses brand and category performance across major Chinese e-commerce platforms.
[1] Shanghai Municipal People's Government. "China unveils 2026 subsidy scheme for home appliance trade-ins." December 2025.
[3] Moojing Market Intelligence. Proprietary e-commerce transaction data covering major Chinese online platforms and an extensive brand set.
This content adheres to Moojing's editorial standards .
Frequently Asked Questions
China's online home appliance sales reached CN¥ 766.35 billion in 2025, up 18.1% year on year, while volume rose 46.8% to 1.71 billion units. Because volume grew far faster than value, average selling prices fell over the period even as the market expanded, which is the pattern we would expect in a market driven by subsidies. Large home appliances, which include air conditioners, refrigerators, washing machines and televisions, accounted for 59.9% of the total at CN¥ 459.4 billion.
It lifted consumption broadly and then began to fade as pent-up demand was absorbed. The programme began in August 2024 and was the defining force in the category, but its effect weakened through late 2025, and the renewed policy announced in December 2025 covers fewer categories with smaller incentives. Refrigerators give the clearest sign that it moved demand forward in time as well as creating it: their growth of 18.6% in 2024 turned into a decline of 3.6%, the pattern of replacement purchases brought forward into the subsidy window.
Cleaning appliances grew on their own momentum, with robot vacuums up 27.0% and floor washers up 16.2%, because households buy them as lifestyle purchases more than as replacements. Electric ovens moved from a 12.8% decline in 2024 to 24.6% growth as the subsidy released latent demand, and central air conditioners grew 52.1%, the strongest movement among major appliances, which reflects whole-home climate systems in premium renovations. Gas stoves fell 38.1% and disinfection cabinets 47.0%, both under structural pressure from urbanisation and changing cooking habits.
Subsidy performance and underlying demand are different things, and the categories separate cleanly on which one they were riding. Products that grew because a subsidy made a replacement cheaper, with refrigerators the clearest case, face a correction once the incentive tapers. Products that grew because a household behaviour changed, such as robot vacuums and floor washers, do not. With the renewed policy covering fewer categories at smaller incentives, the planning question for 2026 is which of those two descriptions fits each of your own lines, because they require opposite responses.


