China Home Appliances Market: Q1 2024 Intelligence
 By Jessie Wang
6 min read
Newer data: China's Online Home Appliance Sales Hit CN¥ 766B in 2025
Executive Summary#
China's online home appliances market exceeded CN¥ 120 billion in Q1 2024, growing 6.5% YoY across three leading Chinese marketplaces, and the recovery ran at two speeds. Major appliances such as TVs, air conditioners and refrigerators generated nearly CN¥ 62 billion in Q1 revenue and gave the market a stable foundation, while the combined cleaning and air management segment reached CN¥ 18.83 billion, up 13.7% YoY, about twice the rate of the market as a whole. Home appliance sales on a leading content-led marketplace grew 90% YoY and passed 13% of the market, which we believe marks a lasting change in how Chinese consumers discover and buy appliances. In Q1 2024 we expected three forces to shape how brands performed that year, namely multi-channel diversification, sub-segment creation and lightweight portability.
Download Full Report#
China's Consumer Economy: Gradual Recovery, Bifurcated Performance#
China's economy improved gradually in Q1 2024, although the recovery varied from sector to sector. Holiday travel was one of the clearer signs of it: the Ministry of Culture and Tourism recorded about 119 million domestic tourist trips over the Qingming holiday in April 2024, 11.5% above the same period of 2019, and CN¥ 53.95 billion in domestic tourism revenue, 12.7% above 2019.
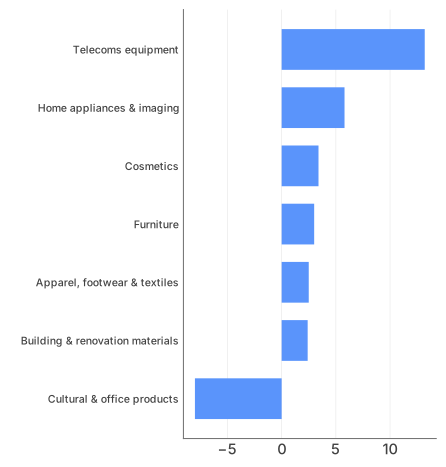
Retail sales growth varied widely across consumer goods categories in Q1 2024, according to the National Bureau of Statistics. Home appliances and imaging grew 5.8% YoY in the quarter after moving between -5.5% and +9.6% through 2022 and 2023, while telecoms equipment grew 13.2% YoY, faster than any other category in the chart below. Building and renovation materials (+2.4%) and furniture (+3.0%) both turned marginally positive after prolonged declines, which may be an early sign that the real estate sector is stabilising.
Home appliances recovery in line with discretionary goods; telecoms leads
CN¥ 120 Billion Online Market: Major Appliances Stable, Cleaning Drives Growth#
Online home appliance sales across three leading Chinese marketplaces exceeded CN¥ 120 billion in Q1 2024, representing 6.5% YoY growth, and the market operated at two distinct speeds. Major appliances, which include TVs, air conditioners, refrigerators and washing machines, generated nearly CN¥ 62 billion in Q1 revenue at roughly flat YoY and kept the market stable, while the smaller lifestyle categories grew considerably faster.
The combined lifestyle appliance segment of cleaning appliances and air management products reached CN¥ 18.83 billion in Q1, up 13.7% YoY.
Consumers bought appliances rationally and deliberately in Q1 2024. The main purchase drivers were resolving a genuine functional need, expressing personal identity, replacing or upgrading an existing appliance, and product recommendations seen on social media, known in China as seeding. Broad, impulse-driven category growth has given way to steady gains in specific sub-segments, although seeding on newer channels, particularly through livestreams and short-video content, can still generate sharp sales spikes for differentiated products.
In Q1 2024 the market favoured brands that created sub-segments, which means identifying consumer scenarios that no product yet serves and engineering a product built for them. Sales of high-penetration categories with limited differentiation, such as vacuum cleaners and rice cookers, were contracting, while categories that offered genuine innovation continued to attract new and replacement buyers.
Content-Led Commerce Gains Share of Online Appliance Sales#
Cumulative online appliance sales across major platforms exceeded CN¥ 600 billion in 2023. In Q1 2024, home appliance sales on a leading content-led marketplace grew 90% YoY and passed 13% of the market, so we believe content-led commerce has become a channel of structural importance for appliance brands, which need to plan for it alongside their established marketplace business.
Emerging Growth Concepts: Six Home Appliance Sub-Categories Lead Q1 2024#
Moojing analysis identified six home appliance sub-categories as the strongest emerging growth concepts of Q1 2024, selected on the basis of revenue scale and growth rate:
- Portable personal care appliances: +5.0% YoY, a portable sub-segment that grew while the wider personal care small appliance market contracted
- Floor washers: +19.1% YoY, where functional innovation sustains strong consumer demand
- Robotic vacuums: +37.6% YoY, where AI-enabled navigation and self-cleaning functions drive upgrade cycles
- Vacuum food sealers: +318.2% YoY, an emerging kitchen appliance supported by consumer interest in food safety and preservation
- Kitchen air conditioners: +358.8% YoY, where purpose-built kitchen cooling addresses a clear consumer need
- Camping and car air conditioners: +1,135.9% YoY, a niche category growing quickly on demand from outdoor activities
The fastest-growing categories on this list were those built for a specific consumer scenario that earlier products did not serve, such as the hot kitchen, the camping tent or the concern about keeping food fresh. We believe generic product claims in established categories no longer generate much consumer engagement.
Three Structural Shifts Shaping the Home Appliance Market in 2024#
In Q1 2024 we expected the home appliance market to face continued headwinds through the year as Chinese consumer spending normalised after the volatility of the pandemic years, and we identified three structural shifts that would determine which brands and categories outperformed.
Trend 1: Multi-Channel Diversification. By 2024 online channels had matured well beyond shelf e-commerce, and livestream commerce, content e-commerce, knowledge e-commerce and search-driven e-commerce each served a distinct consumer entry point and consideration stage. Effective brands therefore build a separate strategy for each channel instead of treating all online channels as one pool of gross merchandise value (GMV). Offline channels are changing too, as lower-tier market penetration, flagship store experiences, partnerships with home renovation companies and super experience stores each play a distinct role in the purchase journey.
Trend 2: Market Segmentation and Personalization. As core appliance categories reach high penetration, manufacturers are developing differentiated sub-segments to capture incremental demand. The air conditioner market shows how this works, since mother and baby air conditioners, kitchen air conditioners, fresh air conditioners and camping air conditioners have each formed a viable sub-market from a consumer scenario that earlier products did not serve. We believe sub-segment creation builds a more durable competitive advantage than incremental feature improvement.
Trend 3: Lightweight Portability. Lifestyle changes since the pandemic have extended the use of home appliances beyond the home, and consumers increasingly want products that travel with them to hotels and outdoor settings. Lightweight, compact and portable appliances are a structural source of growth that cuts across the personal care, kitchen and climate control categories.
About the Data#
This analysis draws on Moojing Market Intelligence (魔镜洞察) data on China's online home appliances market in Q1 2024. Market data covers three leading Chinese marketplaces and measures gross merchandise value (GMV) and sub-segment performance across major, cleaning, air management and personal care small appliance categories. All figures are in Chinese Yuan (CN¥) and reflect online channels only.
This content adheres to Moojing's editorial standards .
Frequently Asked Questions
Online home appliance sales across three leading Chinese marketplaces exceeded CN¥ 120 billion in Q1 2024, up 6.5% year on year, and the market ran at two speeds. Major appliances, namely TVs, air conditioners, refrigerators and washing machines, generated nearly CN¥ 62 billion at roughly flat growth and provided the stable base. The lifestyle segment of cleaning and air management products reached CN¥ 18.83 billion, up 13.7%, about twice the rate of the market as a whole. Cumulative online appliance sales across major platforms exceeded CN¥ 600 billion in 2023, so the quarter sits inside a large and mature category in which growth has narrowed to particular sub-segments.
The fastest growers in Q1 2024 were sub-categories built for a specific, previously underserved scenario. Six stood out on scale and growth rate together: portable personal care appliances (+5.0%), floor washers (+19.1%), robotic vacuums (+37.6%), vacuum food sealers (+318.2%), kitchen air conditioners (+358.8%) and camping and car air conditioners (+1,135.9%). Each serves a particular scenario, such as the hot kitchen, the camping tent or the concern about keeping food fresh, while high-penetration categories with little differentiation, such as vacuum cleaners and rice cookers, were contracting.
They bought rationally and deliberately, and four drivers stood out: resolving a genuine functional need, expressing personal identity, replacement or upgrade timing, and product recommendations seen on social media, known as seeding. Broad impulse-driven category growth had given way to steady gains in specific sub-segments, although content seeding on newer channels could still produce sharp sales spikes for a genuinely differentiated product. The practical reading is that discovery is the variable a brand can actually influence, while the underlying purchase reason is set by whether the product solves something the buyer already recognises as a problem.
Multi-channel diversification, market segmentation, and lightweight portability. On channels, livestream, content, knowledge and search-driven commerce each serve a different entry point and consideration stage, so treating all online channels as one pool of sales loses conversions; appliance sales on a leading content-led marketplace grew 90% year on year in Q1 2024 and passed 13% of the market. On segmentation, sub-segment creation builds a more durable advantage than incremental feature improvement, and air conditioning alone has spawned mother-and-baby, kitchen, fresh-air and camping sub-markets. On portability, appliances now follow the consumer into travel, hospitality and outdoor settings, which cuts across personal care, kitchen and climate control.


