China Outdoor Apparel Surges 22.2% on Camping Boom
 By Jotham Lim
5 min read
Newer data: China Outdoor Lifestyle Market 2026: Scale, Segments, Trust
Executive Summary#
In the Chinese marketplace data behind this analysis, sales of outdoor footwear and apparel reached CN¥ 8.46 billion in the 2023MAT period, a year-over-year (YoY) increase of 22.2%. That growth came in a year when the wider fashion category came under pressure. Premiumization drove the growth, since sales volume came under pressure as well and higher average selling prices account for the whole rise in revenue. Shell jackets were the largest sub-category at CN¥ 2.43 billion after growth of 30.4%, while domestic and international brands both moved further into premium price tiers.
Download Full Report#
Get the complete analysis covering nine major fashion segments, cross-border insights, and brand comparisons.
Revenue Grows While Volume Comes Under Pressure#
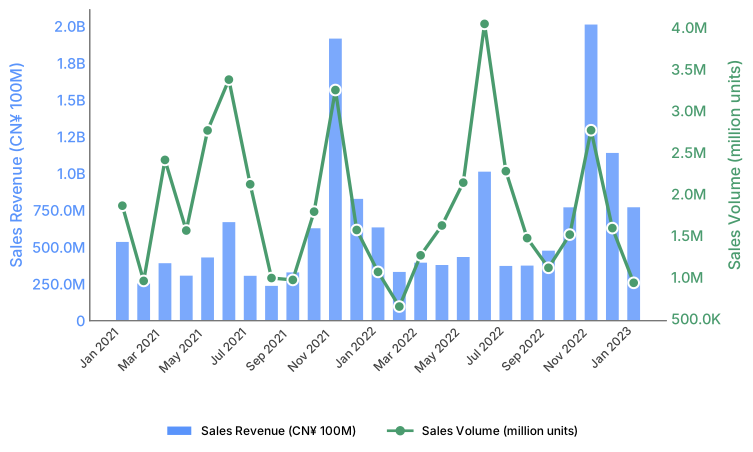
The outdoor segment's revenue grew 22.2%, while sales volume, at 21 million units, came under pressure, so the category's expansion came from higher average selling prices. Brands used livestream sales by influencers to promote outdoor sports styling, which widened the market for premium items. Cold-weather categories such as shell jackets and down jackets, which carry higher unit prices, accounted for much of the purchasing, especially during the Double 11 promotional season.
Revenue grew year on year in every month from January 2022 onward, while volume was under pressure in most months[1]. The strongest revenue growth came in June 2022 (+51.2%) and August 2022 (+58.2%), months that benefited both from seasonal demand and from the move to premium products. Volume picked up for several months in a row for the first time in June to September 2022, as outdoor activity resumed after lockdowns and camping became popular. By Q4 2022, however, volume was under pressure again while revenue kept growing, which indicates that the move to premium products, more than any increase in volume, drove growth in this category.
Sales revenue grows 22.2% YoY to CN¥ 8.46 billion while volume comes under pressure
Shell Jackets and Sun-Protective Clothing Lead Growth#
Shell jackets are the largest sub-category, with CN¥ 2.43 billion in sales revenue and growth of 30.4%, and they have benefited directly from the popularity of camping and outdoor recreation. Trends on social media, from glamping fashion to "Yama Style" techwear, added to consumer demand for outdoor products that are both functional and stylish. Shell jackets, sun-protective clothing and down jackets together account for over 60% of category revenue, which creates both opportunity and risk for brands that depend on these segments.
The fastest-growing sub-categories show that consumers are taking up a wider range of outdoor activities:
- Trail running shoes: +66.6% (CN¥ 95.9 million)
- Sun-protective clothing: +48.4% (CN¥ 1.39 billion)
- Performance underwear: +40.5% (CN¥ 130 million)
- Softshell jackets: +39.5% (CN¥ 223 million)
- Hiking and trekking shoes: +33.9% (CN¥ 580 million)
Growth concentrated in these everyday outdoor categories, while specialised gear for extreme sports such as skiing came under pressure, and we believe this shows that casual outdoor recreation is driving this market more than elite adventure sports.
How Brands Are Moving Into Premium Tiers#
Domestic brands such as Camel (骆驼) have built their outdoor business on livestream marketing and on a broad product range that spans several price points. International outdoor brands such as Arc'teryx (始祖鸟), The North Face and Columbia continue to sell at premium prices, but the price gap between them and domestic brands has narrowed as domestic brands move upmarket. Consumers' willingness to pay higher prices reflects the growing attention they give to product quality, the experience of wearing the product and brand equity.
Price Shift Toward Mid-to-High Tiers#
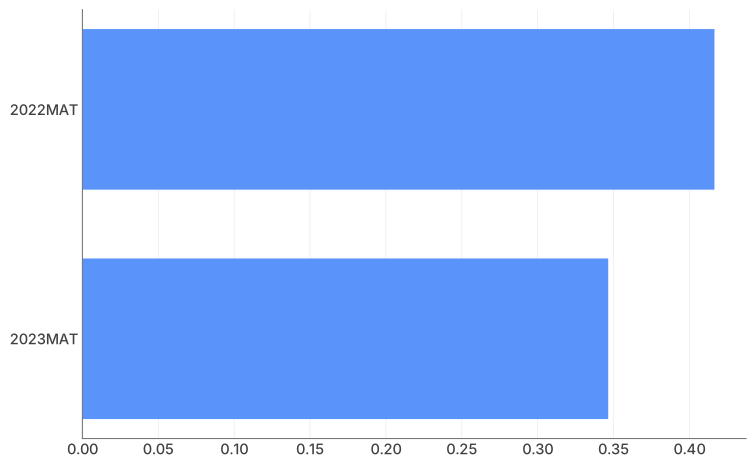
The sub-CN¥ 500 segment's share of revenue fell from 41.7% to 34.7%, a loss of 7.0 percentage points. The gains were spread across several mid-to-high tiers. The CN¥ 500-1,000 segment gained 3.1 pp to reach 23.0%, the CN¥ 1,000-1,500 tier gained 2.1 pp and the CN¥ 2,500+ segment gained 2.2 pp[2]. Only the CN¥ 2,000-2,500 tier lost share (1.1 pp), which suggests that some consumers in this range either traded up to the premium tier or down to the CN¥ 1,500-2,000 range.
This shift reflects several factors that came together:
- Consumers placing greater emphasis on quality and wearing experience
- Growing popularity of higher-priced shell jackets and down jackets
- Brands' use of livestream marketing to support premium pricing
- Government policy support through the "Outdoor Sports Industry Development Plan (2022-2025)" targeting a CN¥ 3 trillion total industry scale
Sub-CN¥ 500 share drops 7.0 pp as consumers trade up to premium outdoor gear
Key Takeaways#
- Outdoor footwear and apparel sales grew 22.2% to CN¥ 8.46 billion, in a year when the wider fashion category came under pressure
- Premiumization drove the growth, with higher average selling prices accounting for the rise in revenue while sales volume came under pressure
- Shell jackets were the largest sub-category at CN¥ 2.43 billion (+30.4%), and sun-protective clothing grew 48.4%
- Domestic brands are moving upmarket with livestream marketing and broad price ranges, which has narrowed their price gap with international outdoor brands
- The sub-CN¥ 500 price tier lost 7.0 pp of revenue share as consumers traded up to mid-to-high segments
More from This Report#
## About the Data
This analysis draws on Moojing Market Intelligence (魔镜洞察) data for one leading Chinese marketplace, covering the 2023MAT period (February 2022 to January 2023). For full methodology and additional insights, see the complete Fashion & Footwear whitepaper.
This content adheres to Moojing's editorial standards .


