China's No-Makeup Look: 645K Mentions, +94% Hybrid Growth
 By Jotham Lim
7 min read
Executive Summary#
Key Findings#
Overview
The no-makeup look was the most discussed beauty style in China in H1 2025, with 645,000 social mentions across major platforms, up 50% YoY. We believe the rise reflects a change in consumer sentiment away from heavily filtered "fake refinement" and toward a natural, authentic look, and the sales data points the same way, with skincare-makeup hybrid products growing fastest, at 94.3% YoY. Premium brands such as BOBBI BROWN and Cle de Peau Beaute have also shown that a premium position can work when it is aligned with this preference for authenticity.
Chinese consumers have grown tired of social media filters and overly polished aesthetics, and the no-makeup philosophy centres on keeping natural traits and showing personality instead of concealing perceived imperfections. The change goes beyond product preference, since it moves the purpose of makeup from concealment to enhancement, which in turn changes how brands develop, market and position their products.
Trend Analysis#
Makeup Style Performance#
Rising and Falling Styles
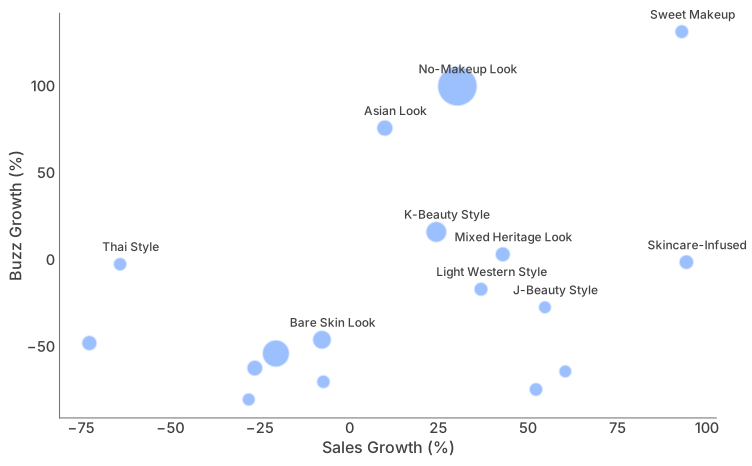
Makeup styles in H1 2025 divided clearly into rising and falling trends. Sweet makeup (sales up 93.0%, buzz up 131.3%) and skincare-makeup hybrids (sales up 94.3%) grew fastest, which reflects consumer demand for products that combine cosmetic enhancement with a benefit for the skin. Styles that were popular earlier fell sharply as consumers moved toward lighter and more natural looks, with smoky eye makeup down 20.6% in sales and 54.0% in buzz, and the new Chinese style down 72.8% in sales.
Sweet makeup (+93.0% sales) and skincare-makeup hybrids (+94.3% sales) capture the strongest growth momentum
Trend Interpretation
The no-makeup look stands out because it combines strong social buzz, up 99.9% YoY, with solid sales growth of 30.2% YoY. We believe this makes the trend both a cultural movement and a commercial opportunity, and that brands which align product development with authentic beauty messaging draw a disproportionate share of consumer attention.
Philosophy Evolution#
Style Keyword Analysis
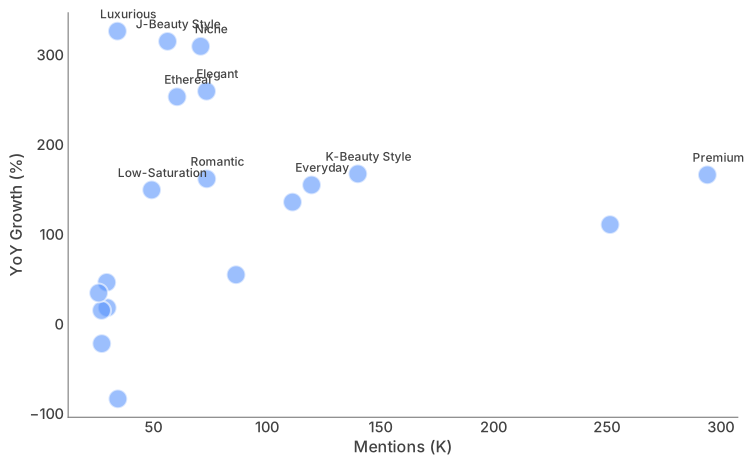
In H1 2025, "premium" and "natural" led social mentions among makeup style keywords, while "luxurious" and "niche" grew fastest year on year. This points to consumer demand for personal expression over mainstream conformity, and it shows how the no-makeup look has moved from a "fake bare-skin technique" to an "authentic aesthetics" philosophy that celebrates natural features instead of concealing them.
Niche (+310%) and luxurious (+327%) styles show strongest buzz growth, signaling personalization demand
What the Keywords Reveal
Mentions of the niche style grew 309.8% and of the luxurious style 326.7%, while mentions of "versatile" fell 83.3%. Consumers increasingly look for distinctive, personal aesthetics over generic, one-size-fits-all approaches, so we believe the trend favours brands with a distinct position and a clear point of difference.
Core Principles#
The Three Principles of the No-Makeup Look
The no-makeup look rests on three principles:
1. Embrace Imperfections. Instead of concealing freckles or redness, consumers use blush and eyeshadow to bring out natural textures, so that perceived flaws become distinctive features.
2. Color Expansion. The trend has moved beyond the idea that nude means light skin, and in H1 2025 it covered a full range of nude tones, including cool browns, deep pinks and greys suited to different complexions and personal styles.
3. Contrast Effects. Consumers are moving away from "all-over minimalism" toward a nude base with intensity in one area to create dimension, for example bare skin with bold brows, or nude lips with shimmer eyeshadow.
Consumer Engagement#
Topic Engagement Trends#
Engagement Patterns
Consumers' wish for "breathable, authentic beauty" is pushing primers and tinted moisturisers toward lightweight finishes that leave the skin's natural texture visible, and the primer category reached CN¥ 3.51 billion in H1 2025, up 4.1% YoY. Concealers have moved from a "full coverage" philosophy to "targeted application", which keeps natural skin texture while making makeup feel lighter.
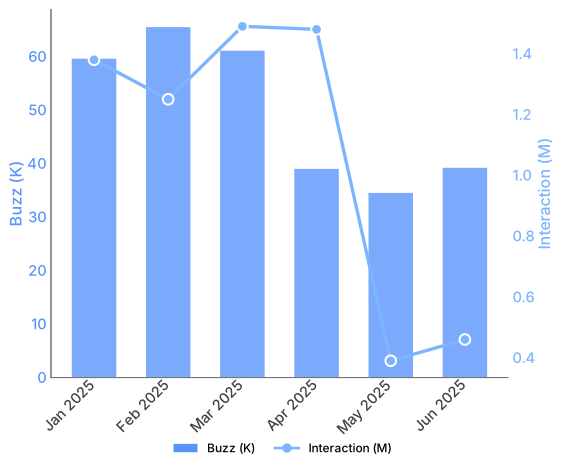
March 2025 peaks at 1.49 million interactions as K-pop influence amplifies the trend
What Drove the Peak
Engagement peaked in March 2025, when light-makeup photos of K-pop idols were widely shared and no-makeup tutorials increased sharply on major social platforms.
Brand Strategies#
BOBBI BROWN#
Brand Positioning
BOBBI BROWN, the color cosmetics brand of the Estee Lauder (雅诗兰黛) Group, was founded by the make-up artist Bobbi Brown, who is credited with pioneering the "no-makeup makeup" look, and the brand's focus on enhancing natural features instead of concealing them matches current consumer sentiment closely.
Products
BOBBI BROWN's base range includes the Vitamin Enriched Face Base and the Sheer Finish Pressed Powder, both of which suit the current preference for a natural, lightweight finish.
NARS#
Brand Philosophy
NARS is one of the prestige brands on which Shiseido concentrates its investment, and its Light Reflecting Pressed Setting Powder and Light Reflecting Foundation are built around a natural, light-reflecting finish.
Cle de Peau Beaute#
Premium Positioning
Cle de Peau Beaute (CPB) Radiant Creamy Base shows how a premium base product can fit the authentic beauty trend. Shiseido started CPB as a luxury line in 1982, and it is one of the prestige brands on which Shiseido concentrates its investment. We believe the Radiant Creamy Base shows that premium positioning remains viable when it is aligned with consumers' wish for natural enhancement.
Product Innovation#
New Product Directions#
Innovation Themes
New no-makeup look products in H1 2025 developed along two lines, the expansion of nude tones and new functional benefits.
Lip and Eye Innovation Trends
Three innovation directions emerged for lip and eye products:
- Low-saturation tones: nude brown and misty pink shades enhance the face naturally without looking artificial
- Multi-functional crossover: single products serve several purposes (eyes, cheeks and lips), which simplifies routines
- Contrasting effects: a nude base paired with one bold accent creates dimension without heavy coverage
Base Makeup Innovation Trends
Base makeup innovation focused on three priorities:
- Multi-effect integration: single products deliver coverage, skincare benefits and sun protection
- Makeup-skincare homology: formulations that care for the skin while providing cosmetic enhancement
- East Asian adaptation: shade ranges developed specifically for East Asian undertones and skin characteristics
How Brands Market the Look#
Marketing Channels#
Integrated Marketing Approach
Social media interaction, celebrity demonstration and runway appearances together shape the movement toward natural authenticity.
Key Marketing Channels
Brands use two main channels to reach no-makeup look consumers:
- Social Platform Marketing: topics on Xiaohongshu (小红书) and Douyin (抖音) such as #HighEndMakeup and #NaturalNoMakeup drive discovery and purchase
- Celebrity Influence: appearances at fashion shows bring no-makeup looks into high fashion
Digital marketing presents the no-makeup look as keeping natural textures such as freckles and redness, using blush to bring out a natural flush and adding a little shimmer eyeshadow for a "tipsy glow" finish.
Conclusion#
Strategic Implications#
Key Takeaways
We believe the no-makeup look is more than a passing trend and signals a lasting change in how Chinese consumers approach beauty.
Download Full Report#
For comprehensive analysis of China's makeup and skincare market trends, including detailed brand performance data and category insights, access the full report.
More from This Report#
About the Data#
This analysis draws on Moojing Market Intelligence data covering H1 2025 (January-June 2025). Social media mentions and buzz data cover conversations across major Chinese social platforms. Moojing analyses brand and category performance across major Chinese e-commerce platforms, and sales figures reflect online retail sales across major platforms.
This content adheres to Moojing's editorial standards .
Frequently Asked Questions
It is a shift from concealment to enhancement, in which consumers keep natural traits such as freckles or redness and show their personality instead of covering perceived imperfections. In H1 2025 it was the most discussed beauty style in China, with 645,000 social mentions, up 50% year on year. Social buzz around it grew 99.9% while sales grew 30.2%, so conversation ran well ahead of purchase, which we believe points to an early cultural shift whose commercial opportunity was still forming in H1 2025.
Skincare-makeup hybrids gained most clearly, with sales up 94.3%, because they deliver cosmetic enhancement and a benefit for the skin at once. Sweet makeup was the other strong performer, with sales up 93.0% and buzz up 131.3%. Moving the other way, smoky eye makeup fell 20.6% in sales and 54.0% in buzz, and sales of the new Chinese style fell 72.8%. In H1 2025 base makeup innovation concentrated on three things: multi-effect integration, so that one product covers, treats and protects; makeup-skincare homology; and shade ranges developed specifically for East Asian undertones. Primers and tinted moisturisers moved toward lightweight finishes that leave skin texture visible, and the primer category reached CN¥ 3.51 billion, up 4.1% year on year.
They point to personalisation over conformity. "Premium" and "natural" led social mentions among makeup style keywords, but the strongest growth came from "niche", up 309.8%, and "luxurious", up 326.7%, while "versatile" fell 83.3%. We read that as consumers turning away from one-size-fits-all looks toward a look that identifies them personally. The colour vocabulary moved with it: nude no longer meant light skin, and in H1 2025 the palette spanned cool browns, deep pinks and greys across complexions. For a brand, the implication is that a distinctive position drew more consumer discussion than a universal one in H1 2025.
Engagement peaked in March 2025 at 1.49 million interactions, amplified by K-pop idols' light-makeup photos and a surge of tutorials on major social platforms. That looks like a celebrity-driven spike, but two things sit underneath it that a single moment does not explain: a stated consumer fatigue with filters and polished aesthetics, and a product-level shift toward formats that keep skin texture visible. We believe the change in attitudes is durable while attention to it is volatile, so brands can plan products around the first and time campaigns around the second.


