China's CN¥98.3B Beauty & Skincare Market: Q1 2024
 By Jotham Lim
7 min read
Newer data: China Online Beauty Sales Held at CN¥ 434.8 Billion in 2025
Executive Summary#
China's online beauty and skincare market reached CN¥ 98.33 billion in Q1 2024, up 1.3% YoY, a modest headline figure behind which the market's structure changed considerably. Volume grew 16.2% YoY to 990 million units, which confirms a shift toward lower average selling prices as consumers moved toward products priced under CN¥ 100. Content-led commerce became a central channel for discovering and buying beauty products, and domestic brands such as Kans (韩束) and Proya (珀莱雅) grew on content-led strategies and hero products. Two consumer demand frameworks, "precision skincare" and beauty as emotional expression, changed both product demand and social media content.
China's Economy in Q1 2024: A Recovery with Caveats#
China's post-pandemic recovery continued in Q1 2024, though unevenly. Services consumption proved resilient: the Qingming holiday saw 119 million domestic tourist trips, up 11.5% on 2019 levels, with tourism revenue reaching CN¥ 53.95 billion (+12.7% vs. 2019). Consumer confidence and household spending propensity improved modestly quarter-on-quarter.
Support for goods consumption was more limited. Social retail growth slowed for three consecutive months, partly because of a strong Q1 2023 comparison base. E-commerce's share of total retail levelled off near 24.2%, which suggests that the increase in online share seen during the pandemic has largely run its course. Within discretionary categories, cosmetics grew 3.4% YoY, which was below the growth of tobacco and alcohol (+12.5%) and telecommunications devices (+13.2%) but ahead of cultural and office supplies (-8.0%).
For beauty brands, we believe this macroeconomic softness moves competition toward value-for-money positioning, domestic-brand alternatives and conversion through content-led commerce. Brands that wait for a broad recovery in consumer spending may lose ground to those already competing on precision and efficiency.
Market Snapshot: CN¥ 98.33 Billion, Volume Outpacing Revenue#
China's total online beauty and skincare market registered CN¥ 98.33 billion in Q1 2024, with revenue growth of just 1.3% YoY, although that figure understates how much movement there was at the sub-segment level. Units sold grew 16.2% to 990 million, and the widening gap between volume and value indicates that average prices fell materially across the quarter.
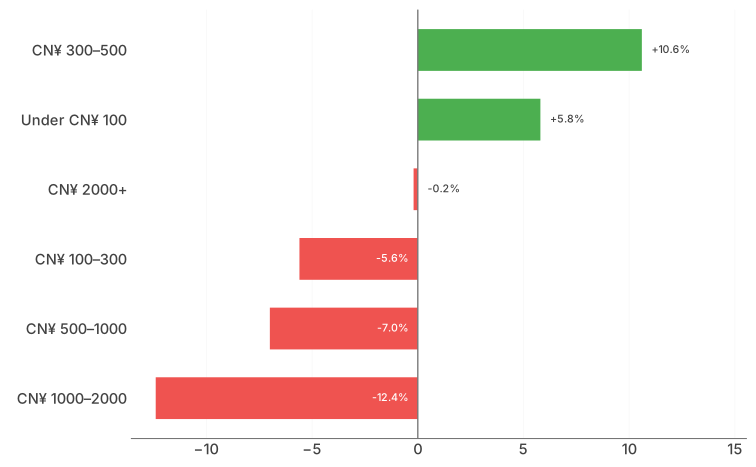
The price segmentation data shows where consumers are spending and where they are not. In beauty, the under-CN¥ 100 tier grew fastest of all segments with revenue growth of 25.3%, while the CN¥ 500–1,000 tier contracted 22.7%. The pattern in skincare is more nuanced. The CN¥ 300–500 tier grew 10.6%, a sign that consumers are willing to pay mid-tier prices for functional skincare marketed on specific efficacy, while the CN¥ 1,000–2,000 and CN¥ 500–1,000 tiers both declined.
Skincare Market Revenue YoY by Price Segment (Q1 2024)
Brand Landscape: Domestic Brands Grow on Content and Hero Products#
Sales became more concentrated among the largest brands during the quarter, even as the total number of registered brands grew 11.7% to approximately 17,000. We believe scale, platform capability and content execution reinforce each other for the largest brands, while the rest of the market becomes more fragmented.
Kans (韩束) built its strategy around co-produced short-form drama content on a leading content-led platform. The brand worked with a well-known creator to produce a short drama series that integrated brand messaging into the storylines, and then combined brand live-streaming with creator live-streaming to build a conversion funnel from first viewing to purchase.
Proya (珀莱雅) took a different route and built its growth around a single hero product, its Energy Peptide Brightening set, supported by ingredient storytelling.
Consumer Demand: Precision Skincare Meets Emotional Beauty#
Two broad patterns in consumer behaviour defined demand in Q1 2024, and although they look opposite, they work together commercially.
The first is precision skincare, in which consumers look for targeted functional solutions in place of products with broad claims. Social media discussion of "precision skincare" grew 686.4% YoY and of "barrier repair" 657.9%, both far ahead of the market's overall voice share growth of 96.2%. Collagen supplementation products grew 58.4% YoY to CN¥ 5.29 billion GMV, and single-use essence ampoules, which are concentrated serums in single-dose vials that preserve potency and hygiene, grew 56.7% to CN¥ 1.83 billion. Barrier repair products reached CN¥ 1.28 billion with sales growth of 9.9%, while social media discussion of them grew much faster.
The second is beauty as an emotional outlet. Young female consumers took up "villain dark lotus," "crazy beauty" and "smoky and world-weary" aesthetics drawn from short dramas and comic culture, and "dark/gothic makeup" products grew 45.0% in revenue and 217.4% in voice share. "Emotional skincare," meaning products positioned around mood-boosting claims or sensory experiences, grew 40.3% in sales. These consumers treat beauty routines as a form of self-expression and stress release as well as everyday care.
The two trends sit comfortably together, since the same consumer may use a precisely formulated ceramide barrier cream in the morning and a bold gothic eye palette at night. For brands, this means that functional precision and emotional appeal can be pursued at the same time as two separate ways to differentiate a product.
Breakout Sub-Segments: Collagen, Ampoules, and Emerging Makeup#
Beyond the headline trends, several specific product concepts grew well above the market average in Q1 2024:
- Collagen supplementation: CN¥ 5.29 billion, +58.4% YoY, the largest breakout category in beauty and skincare
- Single-use essence ampoules: CN¥ 1.83 billion, +56.7% YoY
- Animal-inspired makeup: CN¥ 0.94 billion, +19.5% YoY
- Chinese-inspired makeup: CN¥ 0.35 billion, +18.8% YoY
- Dark/gothic makeup: CN¥ 0.12 billion, +45.0% YoY
The blush category deserves particular attention. Total blush revenue grew 43.3% YoY, and cream blush reached 46.3% of sub-category revenue, up 15.3 percentage points in a single year, which makes cream the preferred format over powder. Blush ranked third in voice share among beauty categories, so it draws far more engagement than its sales alone would suggest. Male consumers accounted for 32.0% of blush social media discussion, which reflects a real expansion of the male grooming audience.
Future Outlook: Three Strategic Themes#
We believe the data from Q1 2024 points to three lasting strategic themes that will shape competitive positioning through the rest of 2024 and beyond.
First, brands need to be fluent in content-led commerce, which is where beauty is increasingly discovered, evaluated and bought. Kans's co-produced drama strategy shows what this can look like. We believe brands that invest in narrative content made for short-video formats, in place of repurposed TV commercials, will build conversion funnels that brands relying on older formats cannot reach.
Second, domestic brands have built strong formulation and operational capabilities. Proya, Kans, Winona and Kefumei (可复美) compete on hero product architecture, ingredient storytelling and go-to-market execution designed for each platform, and their growth does not rest on price alone.
Third, consumer demand is moving toward precision and specific efficacy. Broad claims such as "anti-aging" and "brightening" are losing traction against ingredient-specific and mechanism-specific positioning. Brands that can state clear functional outcomes, such as barrier repair, ceramide replenishment or targeted collagen synthesis, and back those claims with product performance data will build a differentiation that is hard to copy. We believe the "makeup-nourish fusion" hybrid, meaning products that deliver skincare benefits while working as cosmetics, is the most durable direction for product development in the category.
Key Takeaways#
- China's online beauty and skincare market reached CN¥ 98.33 billion in Q1 2024, +1.3% YoY, with units growing 16.2%, which indicates declining average prices across the category.
- Content-led commerce became a central channel for discovering and buying beauty products in the quarter.
- Domestic brands such as Kans (韩束) and Proya (珀莱雅) grew through content-led strategies and hero products, while the number of registered brands rose to approximately 17,000.
- Social media discussion of "precision skincare" and "barrier repair" grew 686.4% and 657.9% YoY respectively, which confirms a lasting shift in consumer demand toward targeted functional solutions.
- Collagen supplementation (CN¥ 5.29 billion, +58.4%) and single-use essence ampoules (CN¥ 1.83 billion, +56.7%) are the largest-scale, fastest-growing product concepts in the market.
- Cream blush reached 46.3% of blush category revenue, up 15.3 percentage points in one year, and male consumers accounted for 32.0% of blush discussion.
About the Data#
This analysis draws on Moojing Market Intelligence (魔镜洞察) data on China's online beauty and skincare market in Q1 2024 across several leading Chinese e-commerce marketplaces. Social media voice share data is drawn from major Chinese social platforms. All YoY comparisons reference Q1 2023.
Download the Full Report#
This content adheres to Moojing's editorial standards .
Frequently Asked Questions
CN¥ 98.33 billion, up just 1.3% year on year, a modest headline figure behind which the market's structure changed considerably. Units grew 16.2% to 990 million, so average prices fell materially across the quarter. The price data shows where: in beauty the under-CN¥ 100 tier led everything at +25.3% while the CN¥ 500–1,000 tier contracted 22.7%. Skincare is more nuanced: the CN¥ 300–500 tier grew 10.6%, which says consumers will still pay mid-tier prices for functional skincare marketed on specific efficacy, while both higher tiers moved down. Consumers traded down selectively, and a premium price had to be justified by function.
At the top, yes. Sales became more concentrated among the largest brands during the quarter, even as the number of registered brands grew 11.7% to around 17,000. The market is polarising, since scale, platform capability and content execution reinforce each other for the largest brands while the rest of the market fragments further, so more brands entering the category does not mean more brands succeeding.
Consumers seeking targeted functional solutions rather than broad-claim products. Discussion of precision skincare grew 686.4% year on year and barrier repair 657.9%, both far ahead of the category's overall voice share growth of 96.2%. The commercial follow-through is visible. Collagen supplementation grew 58.4% to CN¥ 5.29 billion, and single-use essence ampoules, which are concentrated serums in single-dose vials that preserve potency and hygiene, grew 56.7% to CN¥ 1.83 billion. Barrier repair products reached CN¥ 1.28 billion at +9.9%, with far stronger social validation than sales. Broad claims such as "anti-aging" and "brightening" are losing traction against ingredient- and mechanism-specific positioning.
It does not conflict, because it runs in parallel. Younger female consumers adopted expressive aesthetics drawn from short drama and comic culture, and the numbers follow. Dark and gothic makeup grew 45.0% in revenue and 217.4% in voice share, and emotional skincare positioned around mood and sensory experience grew 40.3%. Animal-inspired makeup reached CN¥ 0.94 billion (+19.5%) and Chinese-inspired makeup CN¥ 0.35 billion (+18.8%). The same buyer can reach for a precisely formulated barrier cream in the morning and a bold eye palette at night. Blush shows the combination clearly: revenue rose 43.3%, the cream format crossed 46.3% of the sub-category, up 15.3 points in a year, and male consumers accounted for 32.0% of blush discussion.


