China's Sleep & Hair Growth Device Markets: Two High-Growth Niches
 By Quan Wenjun
6 min read
Executive Summary#
China's online personal care and medical device markets together exceeded CN¥ 139 billion in 2023, and two niche categories grew faster than the wider market. Sales of sleep devices (睡眠仪) reached CN¥ 390 million (+5.4% YoY) and sales of hair growth devices (生发仪) rose to CN¥ 440 million (+86.9% YoY). In both categories most sales go to small or niche brands and content-led channels are still at an early stage, so we believe there is room for larger brands that can bring technology credentials, scale and investment in social media.
Download Full Report#
Get the complete brand-level analysis, pricing breakdown, social media buzz data, and strategic entry framework for both categories.
Download China's Sleep Device & Hair Growth Device Market: Trend Insights →
A CN¥ 139 Billion Market with Two Fast-Growing Niches#
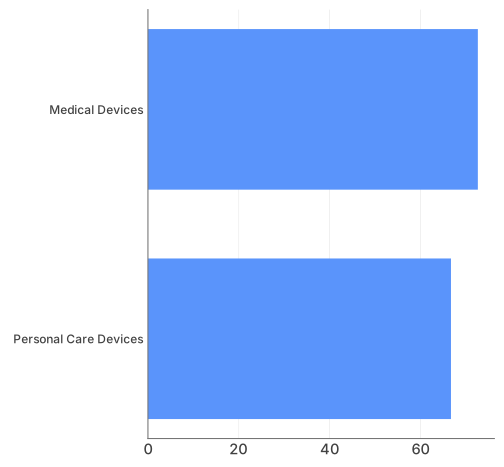
China's online sales of personal care, health and massage devices came to CN¥ 66.73 billion (+6.2% YoY) in 2023, while the wider medical devices category reached CN¥ 72.65 billion (+2.9% YoY). The faster growth of personal care devices reflects consumer demand for wellness and self-care technology at home, a trend that gathered pace after the pandemic and has continued since.
Within both categories, growth is concentrated in niche segments. When we screened for categories with sales above CN¥ 10 million and year-on-year growth above 20%, sleep devices and hair growth devices stood out as the two strongest opportunities among personal care devices.
China online sales of personal care and medical devices, 2023 (CN¥ bn)
Sleep Devices: Steady Growth and Room in Content-Led Channels#
China's sleep device (睡眠仪) market reached CN¥ 390 million (+5.4% YoY) in 2023. The growth rate is moderate, but the structure of the market tells us more: about 500 brands are active in the category, most of them small, niche or white-label OEM manufacturers, and many of them sell through Taobao (淘宝).
Sales followed an unusual seasonal pattern, with strong first and third quarters while the 618 and Double 11 promotional festivals fell short of expectations. That is unlike most consumer electronics categories, where promotional events bring large sales spikes. We believe it shows that sleep devices have not yet become part of consumers' promotional shopping, so brands that invest in campaigns tied to these occasions could change how the category performs at the main commercial events.
Concentration in the market is low, and newer entrants such as Panapopo, Youruide (优瑞德) and BrainCo have shown that investment in channels and content can build a business quickly in a young category.
Content-led channels remain at an early stage for sleep devices, since larger brands have not yet committed to distribution or content seeding there. This gives early entrants that invest in platform-native content and influencer partnerships the chance to establish themselves first.
Hair Growth Devices: A Fast-Growing, Premium-Priced Category#
China's hair growth device (生发仪) market is one of the fastest-growing niches in personal care technology, with sales of CN¥ 440 million (+86.9% YoY) in 2023 and a peak of CN¥ 58.54 million in November. We believe the near-doubling reflects growing awareness of hair loss and thinning as health concerns among consumers, along with wider acceptance that technology-based solutions can deliver measurable results.
The category is priced at the premium end, with consumers spending CN¥ 3,500–7,000 on a device. At that price they look for the brand assurance, product quality guarantees and customer service that official flagship stores provide, so much of the category's sales go through flagship stores.
Competition in the category is fragmented and consumer awareness of brands is still immature. Unlike more established health device segments, the category has no brand with dominant mind share, which leaves room for a well-funded entrant with credible positioning to build a leading position.
Key consumer demand drivers include:
- Rising urban prevalence of hair loss concerns across both male and female demographics
- Growing acceptance of Low-Level Laser Therapy (LLLT) and red light technology as evidence-backed solutions
- Willingness to invest in premium products when backed by clinical claims and brand credibility
- Social media amplification of hair care routines, creating aspirational purchase triggers
Market Size Comparison: Sleep vs. Hair Growth Devices#
The two categories are similar in size, with sleep devices at CN¥ 390 million and hair growth devices at CN¥ 440 million, but their growth differs widely. Hair growth devices grew 86.9% year on year, which shows a category expanding quickly, while sleep devices grew 5.4%, which points to a market developing more steadily from a stable base.
This difference calls for different entry strategies. Hair growth devices offer a more immediate growth opportunity but require investment in technology credibility and premium positioning. Sleep devices are less contested, particularly in content-led channels, so a first mover with differentiated technology and reach on social media could change the category relatively quickly.
Social Media: Both Categories Are at an Early Stage#
Social media buzz is a useful forward-looking indicator for both categories. Posts about sleep devices totalled about 27,000 across three major Chinese social platforms in 2023, growing 27.1% QoQ. A single post by a sceptical blogger set off a wide organic debate, which shows that the category can produce viral moments even when brands invest little.
Buzz about hair growth devices is much larger, at about 155,000 posts (+1,964.7% QoQ) in 2023. Brands use retweet mechanics, red packet campaigns and occasion-linked content to build awareness around the Qixi Festival (Chinese Valentine's Day) and the Double 11 promotional period.
In both categories we believe investment in social seeding can bring large returns in awareness and conversion, since no large brand has yet invested in social media at the level that would establish clear leadership of either category.
Key Takeaways#
- China's personal care devices (CN¥ 66.73 billion, +6.2% YoY) and medical devices (CN¥ 72.65 billion, +2.9% YoY) both grew in 2023, and the strongest opportunities sit in niche segments.
- Sleep devices reached CN¥ 390 million (+5.4% YoY) in 2023, with about 500 brands competing, content-led channels still at an early stage and promotional festivals below their potential.
- Hair growth devices rose to CN¥ 440 million (+86.9% YoY), a premium-priced category in which consumer awareness of brands is still immature and no brand holds a dominant position.
- Social buzz supports entry, with sleep device posts growing 27.1% QoQ and hair growth device posts growing 1,964.7% QoQ, and both categories respond strongly to social seeding by brands.
- Larger technology brands have yet to commit to either market, which leaves room for a credible, well-resourced entrant with technology positioning and distribution in content-led channels.
About the Data#
This analysis is based on Moojing Market Intelligence (魔镜洞察) data covering China's online sleep device and hair growth device markets for full-year 2023. Market data covers transactions on Tmall (天猫), Taobao (淘宝), JD.com (京东), and Douyin (抖音). Social media data covers Weibo (微博), Douyin, and Xiaohongshu (小红书). All figures are in Chinese Yuan (CN¥) and reflect online channels only.
Moojing Market Intelligence (魔镜洞察) analyses brand performance and consumer trends across China's major e-commerce and social platforms. For inquiries, contact info@moojing-global.com or visit moojing-global.com.
This content adheres to Moojing's editorial standards .


