China Air Fryers: Health and Price Drove Five-Year Growth
 By Quan Wenjun
4 min read
Executive Summary#
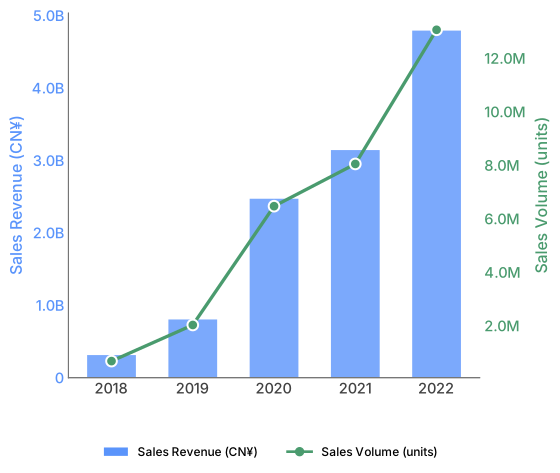
Air fryers were the largest category in China's online desktop cooking appliance market in 2022, with CN¥ 4.79 billion in sales on two leading Chinese marketplaces[1], more than double the second-largest category, and year-on-year (YoY) growth of 52.5%. Sales rose from CN¥ 312 million in 2018 to CN¥ 4.79 billion in 2022, a 15.4-fold increase over five years. We believe the growth was driven by health-conscious consumers, by social media content and by falling prices that brought the product within reach of the mass market. This analysis examines the structural forces behind the growth of air fryers and the brand strategies that met the new demand.
Download Full Report#
Get the complete analysis with additional data, methodology details, and brand-level insights across all eight desktop cooking appliance categories.
Download the Full Q1 2023 Desktop Cooking Appliances Whitepaper →
Five Years of Growth#
The air fryer has been the main growth story in China's desktop cooking appliance market. Revenue grew 15.4 times over five years, while volume rose from 675,000 units to 13.1 million units, a 19.3-fold increase that we believe reflects lasting structural demand and goes well beyond a cyclical upturn. Growth accelerated in 2022 to 52.5% YoY, which suggests that the category has not yet reached a plateau even at its current scale.
Air fryers achieve explosive five-year growth from CN¥ 312 million to CN¥ 4.79 billion
Three Structural Growth Drivers#
Three forces explain the rise of the air fryer, and each has strengthened the others:
- Health positioning: Air circulation heating allows "oil-free" cooking, which fits the government's "Healthy China 2030" initiative[2] and the growing interest in wellness among urban consumers
- Social media content: The "everything can be air-fried" content trend on Douyin and Xiaohongshu brought a steady flow of organic discovery, which turned curiosity into purchases
- Lower prices: Larger brands competed hard at accessible price points, which widened the market from early adopters to mass-market consumers
Volume grew faster than revenue (19.3 times against 15.4 times), which shows that the average selling price (ASP) came down modestly as the category moved from niche to mainstream pricing. Brands such as Shanben and Aux grew on value positioning at low average prices, and the scale of the increase in demand more than made up for the lower prices.
The Air Fryer's Share of Desktop Cooking#
Air fryers accounted for CN¥ 4.79 billion of the CN¥ 12.28 billion desktop cooking appliance market in 2022, approximately 39% of category Gross Merchandise Value (GMV), which is a large share for a category that barely existed five years earlier.
How Brands Competed#
Competition among air fryer brands is intense, and the fastest growth came at the mass-market price tier, where brands such as Shanben and Aux competed on value with low average prices. We believe this shows that the mass-market tier generated most of the new demand. Mid-priced products without clear differentiation face pressure from premium innovators on one side and from value brands on the other.
We believe air fryers have entered a phase of growth driven by volume, in which scale, distribution efficiency and cost competitiveness decide a brand's position in the market.
Key Takeaways#
- Air fryer sales grew 15.4 times in five years to reach CN¥ 4.79 billion in 2022, up 52.5% YoY, about 39% of the desktop cooking appliance market
- Volume grew 19.3 times to 13.1 million units, which points to lasting structural demand in the category
- Health positioning, social media content and lower prices reinforced one another and kept the category growing
- Value positioning at low average prices, the strategy of brands such as Shanben and Aux, met the largest share of new demand
- Air fryers have taken demand from electric ovens, whose sales came under pressure after 2020 as consumers moved to more compact appliances
More from This Report#
## About the Data
This analysis draws on Moojing Market Intelligence data covering the 2018-2022 period, from two leading Chinese marketplaces. Moojing analyses brand and category performance on Chinese e-commerce platforms. For full methodology and additional insights, see the complete Desktop Cooking Appliances whitepaper.
This content adheres to Moojing's editorial standards .


