China Health Supplements: Q1 2024 Market Intelligence
 By Jotham Lim
9 min read
Newer data: China Online Health & Wellness Sales Rose 9.5% in H1 2026
Executive Summary#
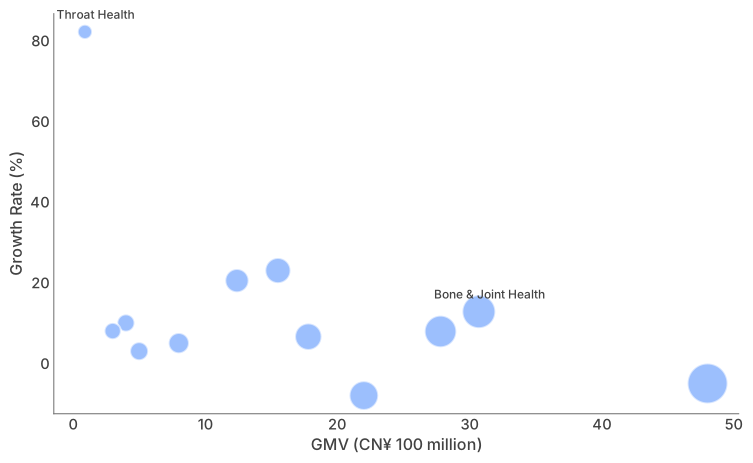
China's online health supplements market exceeded CN¥ 25 billion in Q1 2024, up 2.0% YoY, and the modest headline rate hides large differences between sub-segments. Oral beauty, historically the market's largest category, lost momentum, while eye health (+20.5%), sports nutrition (+23.0%), liver health (+13.0%) and throat health (+82.2%) all grew strongly. Social media discussion points the same way, with discussion of liver health up 50.9% YoY and eye health up 40.5%, while conversation about immunity fell 53.2%. For brands already in the health supplements market or planning to enter it, we believe Q1 2024 marks a turning point, as a category once defined by broad immunity products moves towards targeted health solutions built around specific everyday situations. By Q1 2024 those solutions attracted both consumer attention and a commercial premium.
China's Macro Context: A Selective Consumer Recovery#
China's economy continued a gradual recovery in Q1 2024. Per capita disposable income and consumer expenditure trended upward, although the recovery remained uneven across categories. Travel and tourism rebounded strongly, and the Qingming 2024 holiday recorded 119 million domestic tourist trips (+11.5% against 2019) and CN¥ 53.95 billion in tourism spending (+12.7% against 2019). Consumer confidence, however, remained below the previous year's level, which reflects lasting post-pandemic caution and continued weakness in the real estate sector.
Online retail's share of total retail consumption reached 24.2%, a level that analysts describe as close to a near-term ceiling. Category performance in Q1 2024 varied widely: tobacco and alcohol grew 12.5% YoY, communications equipment 13.2% and food and beverages 9.6%, while cultural and office supplies fell 8.0%. Health supplements' gain of 2.0% sits within the broader Chinese and Western medicine category, which grew 5.8%, a respectable result for a market shaped by consumers' changing health priorities.
Online Health Supplements: CN¥ 25 Billion and New Brands in Content-Led Commerce#
Behind the CN¥ 25 billion total, the way supplement brands reach consumers is changing. Established international and domestic brands such as Swisse (斯维诗) and By-Health (汤臣倍健) have built their businesses on clinical heritage and brand trust. Newer brands such as Renhe (仁和), WonderLab and Five Female Doctors (五个女博士) design products for social sharing, taste and conversion through live-streaming commerce. We believe content-led commerce is no longer optional for health supplement brands, and brands that treat it as a minor addition to their channel mix risk missing one of the market's main sources of growth.
Sub-Segment Performance: Where the Market Is Growing#
The most important finding of Q1 2024 for strategy is the gap between the high-growth sub-segments and oral beauty, historically the market's largest functional segment by GMV, which lost momentum while five sub-categories grew strongly.
Q1 2024 Health Supplements Sub-Segment: GMV vs. Growth Rate
Eye Health: Gummies and the Renhe Approach#
Eye health was the sub-category that stood out in Q1 2024, with GMV up 20.5% YoY, and one product, Renhe's Blueberry Lutein Ester Gummy, shows how a brand can enter the segment.
The shift in dosage form within eye health products is large. Gummies grew 89.7% YoY and capsules 3.4%, while tablets fell 36.9% and sachets fell 99.6%, which means they have almost left the category. We believe this is a lasting change in format preferences among younger consumers, who treat daily health products as part of their lifestyle routine and are less inclined to think of them as a medical intervention.
Renhe's approach is a useful reference for any brand entering a health supplement sub-segment through content-led commerce. It positioned the product for a specific and sympathetic consumer, parents buying for their children, and priced it at an accessible mass-market level of CN¥ 29.9 per bottle. It formulated it in the format consumers prefer, gummies with clean-label claims, and seeded it through creators whose audiences match the buyer, in family and mother-and-baby content.
Among eye health ingredients, beta-carotene grew fastest (+95%), while lutein ester (+42%) and blueberry extract (+35%) remain the core ingredients by sales. Astaxanthin (-5%) is the only ingredient whose sales fell, which suggests that consumers still prefer the established ingredients with the strongest evidence behind them.
Liver Health: Scenario-Driven Content and the Spring Season#
Liver health grew approximately 13.0% YoY in Q1 2024, and social media discussion of it rose 50.9%, the fastest discussion growth of any health topic in the analysis. The main driver is seasonal, since in traditional Chinese medicine spring is the liver's season and Chinese consumers have absorbed this idea deeply into how they buy. Q1 includes the Qingming holiday, which brings a large amount of liver health content and buying.
Social media discussion of liver health is organised around situations: 56.9% of posts centre on usage contexts (late nights, 39.1%; social drinking, 32.5%; overtime work, 18.4%), while 31.3% address efficacy and only 11.8% discuss ingredients. This has a direct commercial implication, since brands that base their content on these familiar situations, in place of clinical claims about liver function, earn more organic engagement and get more from their KOL seeding.
Milk thistle (奶蓟草) accounts for 62.7% of ingredient-level discussion. Hovenia dulcis grew 25%, faster than any other liver health ingredient, and brands such as Beijing Tongrentang and Huatuo Guoyao offer products made with it. Traditional Chinese medicine ingredients such as angelica and astragalus are losing ground as consumers turn towards internationally recognised ingredients with stronger evidence behind them.
Swisse has built its liver health business through product, endorsement and live experiences. It upgraded its milk thistle tablet to a second-generation formulation with added choline and broccoli seed, concentrated its spending on celebrity endorsement (Dilraba Dilmurat and Zhou Ye) and on sponsoring the iQIYI variety show Riding the Wind 2024 (乘风2024). It also dramatised the late-night usage scenario through an offline "Full-Power Party" event. Each of these rests on the same insight about consumers, who see liver health as a question of everyday performance and lifestyle more than as a medical concern.
Social Media as the Main Route to Discovery and Purchase#
Across health supplement sub-categories, social media has become the main channel through which consumers discover products, come to trust them and decide to buy. The Q1 2024 social media discussion data shows the direction clearly: discussion of eye health (+40.5%), anti-aging (+43.0%), liver health (+50.9%) and skin health (+19.6%) is rising, while discussion of immunity enhancement fell 53.2% and sports health 37.2% from their COVID-era peaks.
We believe these movements in discussion volume are early indicators of how categories will perform commercially. In eye health and liver health, rising social media discussion has been followed by GMV growth within one to two quarters, which makes social media analysis a useful forward-looking input for brands deciding which categories to enter and where to invest.
The most effective content in Q1 2024 was built around situations, and claims played a smaller part. For liver health, late-night and social drinking scenarios work best, and for eye health, screen fatigue, myopia and study pressure resonate most with working-age buyers and parents. Brands that explain the science behind their ingredients, such as the bioavailability advantage of lutein ester or the silymarin content of milk thistle, are building the trust that turns social engagement into repeat purchases.
Future Outlook: Four Forces Shaping China's Health Supplements Market#
We believe four forces will shape the market over the next 12-24 months.
Compound and multi-functional formulations displace single-ingredient products. Consumers know more about ingredients than they did, and products that meet two or more health needs through scientifically validated compound blends should command premium prices and stronger repurchase. Probiotics, collagen and whey protein are the most attractive commercially, since each combines large scale and high growth with wide familiarity among consumers.
Snackification accelerates across sub-categories. Gummies and functional drinks are taking share from tablets and capsules in eye health and across the broader supplements market. Brands that have not yet developed snack-format line extensions risk losing relevance, particularly with consumers under 35, who drive much of the growth in content-led commerce.
Content-led commerce becomes a core channel. Brands that lack live-streaming commerce capability, KOL seeding programmes matched to health sub-categories and content teams able to produce scenario-driven short video in volume will find it increasingly difficult to compete in content-led commerce.
Targeting replaces breadth as the organising principle of brand strategy. The consumer shift from broad immunity products to the management of specific health needs, such as eye health for screen fatigue, liver health for urban lifestyles and sports nutrition for fitness, is lasting. It is driven by demographics: an ageing population on one side and a younger generation with high health awareness on the other. We believe brands that build a clear position in one or two targeted sub-segments will create more durable brand equity and market more efficiently than brands that keep a broad portfolio across immunity and oral beauty.
Key Takeaways#
- China's online health supplements market exceeded CN¥ 25 billion in Q1 2024, up 2.0% YoY, and the modest headline growth hides large differences between sub-segments.
- Eye health (+20.5%) and sports nutrition (+23.0%) are among the fastest-growing sub-segments, while oral beauty and immunity enhancement have lost momentum as those categories mature.
- Gummy-format eye health products grew 89.7% YoY, while tablets fell 36.9% and sachets 99.6%, and we believe the move of health supplements into snack formats is a lasting trend.
- Social media discussion of liver health grew 50.9% YoY, driven by content about everyday situations such as late nights, drinking and overtime, and milk thistle accounts for 62.7% of ingredient-level discussion.
- Renhe's Blueberry Lutein Ester Gummy (CN¥ 29.9 per bottle) shows how an accessible price, a snack format and seeding in content-led commerce can work together in 2024.
About the Data#
This analysis draws on Moojing Market Intelligence (魔镜洞察) data on China's online health supplements market in Q1 2024. Market data covers three leading Chinese marketplaces and measures GMV and sub-segment performance. Social media data is drawn from major Chinese social platforms. All figures are in Chinese Yuan (CN¥) and reflect online channels only.
Download the Full Report#
This content adheres to Moojing's editorial standards .
Frequently Asked Questions
It exceeded CN¥ 25 billion in Q1 2024, up 2.0% year on year, a modest number that concealed a structural reordering underneath. Sub-segment performance diverged sharply: throat health grew 82.2%, sports nutrition 23.0%, eye health 20.5% and liver health 13.0%, while oral beauty, historically the largest functional segment, lost momentum. For context, online retail reached 24.2% of total retail consumption in the period and the wider Chinese and Western medicine category grew 5.8%. Reading the aggregate alone would tell you the category had stalled; reading the segments tells you it had rotated.
Eye health grew 20.5% year on year, and the format shift inside it was large: gummies grew 89.7% and capsules 3.4%, while tablets contracted 36.9% and sachets effectively left the category at -99.6%. We believe this reflects younger consumers treating a daily health product as part of a lifestyle routine rather than as a medical intervention, and format is how that distinction gets expressed. On ingredients the picture is more conservative: beta-carotene posted the strongest growth at +95%, with lutein ester (+42%) and blueberry extract (+35%) still the commercially dominant inputs and astaxanthin the only one contracting at -5%.
Four moves that reinforce each other. Position for a specific, sympathetic buyer, here parents buying for children. Price at an accessible mass-market level: CN¥ 29.9 per bottle. Formulate for the format preference, meaning gummies with clean-label claims. And seed through contextually relevant creator communities, meaning family and mother-and-baby content rather than health-authority content. None of the four moves is novel on its own; the effect comes from all of them pointing at the same buyer.
Seasonally, and scenario-first. In traditional Chinese medicine spring is the liver's season, and the Qingming holiday falls inside Q1, and that holiday itself recorded 119 million domestic tourist trips, +11.5% against 2019, and CN¥ 53.95 billion in tourism spending. Liver health grew about 13.0% with social discussion up 50.9%, the fastest of any health topic in the analysis. The discussion architecture is the actionable part: 56.9% of posts centre on usage contexts (late nights at 39.1%, social drinking 32.5%, overtime work 18.4%), while 31.3% address efficacy and only 11.8% discuss ingredients. Content anchored in those scenarios outperforms clinical liver-function claims, and milk thistle already carries 62.7% of ingredient-level discussion.


