Infant Lutein Surpasses CN¥ 800M as Eye Health Fears Rise
 By Jessie Wang
4 min read
Executive Summary#
China's infant lutein market exceeded CN¥ 800 million in sales value in 2024, on approximately 4.73 million units sold, which makes it one of the fastest-growing segments in children's nutrition. Its growth comes from parents' rising concern about children's screen time and myopia, and from a gummy format that accounts for 82.8% of sales. Distribution is also unusually balanced, as the three channels in our data each contribute roughly 30% of sales. This analysis looks at seasonal sales patterns, the structure of brand competition, price segments and product formats in this fast-changing market.
Download Full Report#
Get the complete analysis covering infant nutrition, children's vision health, probiotics, and supplement formulation trends across China's child health and wellness market.
Balanced Distribution Sets Lutein Apart from Other Supplements#
The infant lutein market differs from most supplement categories in how evenly its sales are spread, since each of the three channels in our data contributes roughly 30% of the total. We believe this reflects different ways of reaching parents, with search-driven purchasing on established marketplaces, trust-driven buying on marketplaces that parents associate with authentic products, and content-driven conversion on content-led platforms.
Monthly sales follow a clear seasonal pattern, with the strongest period in October and November around the Double 11 shopping festival, when parents appear to buy ahead of the festival. The June 6.18 festival is a second sales window, and July is a third, as content-led platforms run summer campaigns at a time when children spend more time on screens during the school break.
Growth Is Spread Across Many Brands#
The market has not yet consolidated, as several brands of very different sizes grew rapidly in 2024 and growth rates among the larger brands varied widely. We believe this shows that the category is still open to new entrants, and that brands reached scale in 2024 through differentiated entry strategies.
Mid-Range Pricing Reflects Content Commerce Dynamics#
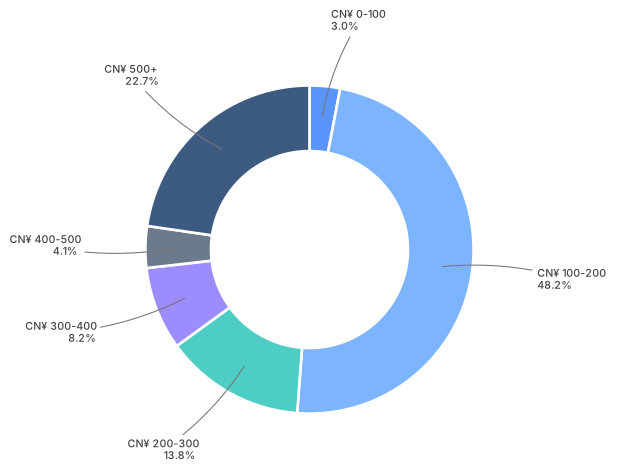
Price segments vary across channels, in line with differences in consumer profiles and purchasing behaviour. On a leading content-led marketplace, the CN¥ 100-200 price segment accounts for 48.2% of sales, which makes it the mainstream price point for purchases driven by content. The CN¥ 500+ segment holds a notable 22.7% share, and it consists mainly of multi-product bundle packs that combine lutein with complementary nutrients such as calcium or DHA.
The CN¥ 100-200 range accounts for 48.2% of lutein sales on a leading content-led marketplace, with premium bundles above CN¥ 500 at 22.7%
Gummies Account for 82.8% of Sales#
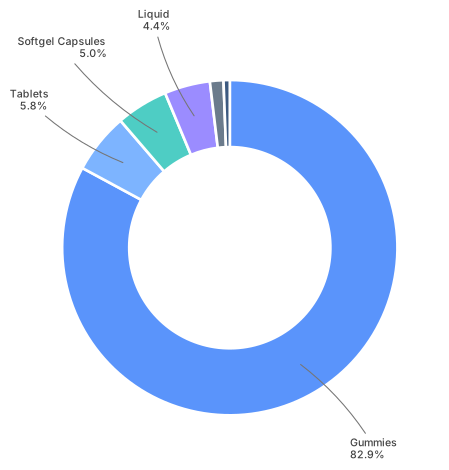
While dosage forms are still competing in adult supplements, the infant lutein market has already settled on one format. Gummy formulations account for 82.8% of sales, a large majority that reflects how well the format solves the main problem in children's supplements, which is getting children to take them every day. The pleasant taste and playful format encourage the consistent daily use on which brands' eye-health positioning for lutein relies.
Gummy formulations account for 82.8% of infant lutein sales
Key Takeaways#
- China's infant lutein market exceeded CN¥ 800 million in 2024 with 4.73 million units sold, driven by parents' rising concern about children's screen time and myopia.
- The category has not yet consolidated, and several brands of different sizes grew rapidly in 2024, which suggests it remains open to new entrants.
- Sales are spread roughly evenly across the three channels in our data, at roughly 30% each, which sets lutein apart from most supplement categories.
- On a leading content-led marketplace, 48.2% of sales fall in the CN¥ 100-200 range, while bundle packs above CN¥ 500 account for 22.7%.
- Gummy formulations account for 82.8% of sales, so innovation within gummies is likely to be worth more to brands than diversifying into other dosage forms.
- Seasonal peaks in October and November (Double 11) and in June (6.18) create concentrated marketing windows, and July offers an opportunity for content-led marketing tied to parents' concerns about summer screen time.
More from This Report#
About the Data#
This analysis draws on Moojing Market Intelligence data covering China's infant lutein market on four leading Chinese marketplaces, grouped into three channels, for the full year 2024. Moojing analyses brand and category performance across major Chinese e-commerce platforms. For full methodology and additional segment-level insights across infant nutrition, children's vision health, and supplement formulation trends, see the complete Child Health & Wellness whitepaper.
Moojing Market Intelligence (魔镜洞察) provides e-commerce analytics and consumer insights internationally. For inquiries, contact info@moojing-global.com.
This content adheres to Moojing's editorial standards .


