China's Online Beverage Market H1 2024: Tea Leads CN¥ 17.5B
 By Jotham Lim
7 min read
Newer data: Beverage Efficacy Claims Grew 26.6% in China in H1 2026
Executive Summary#
China's online beverage market reached CN¥ 17.51 billion in H1 2024, up 14.2% YoY, and beneath that headline the mix of what consumers buy is changing quickly. Tea beverages more than doubled, growing 117.5% YoY to CN¥ 2.68 billion, while electrolyte drinks posted the highest growth rate in the category at 132.7%, and content-led marketplaces became an important place for tea beverage launches. For brands, the implication is that the market is growing, but the growth is flowing to specific sub-categories and channels, which calls for deliberate investment choices in place of broad-based spending.
Market Overview: CN¥ 17.5 Billion and Accelerating#
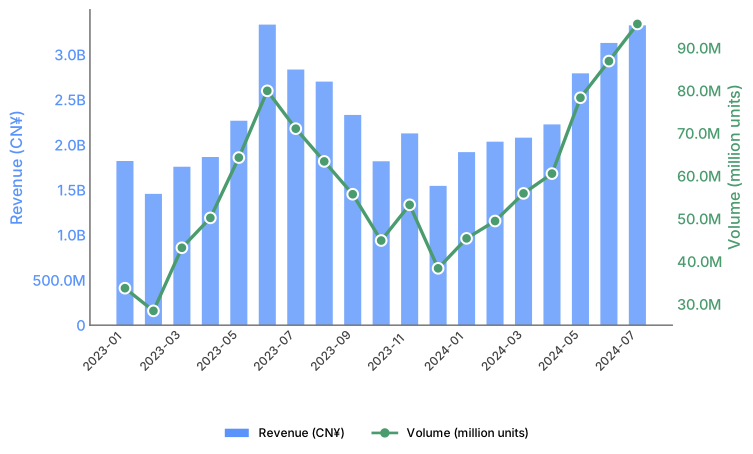
China's online beverage market delivered its strongest first half on record in H1 2024. Total revenue across leading Chinese marketplaces reached CN¥ 17.51 billion for January through July, an increase of 14.2% year-on-year. Growth was not front-loaded, because the summer peak season from May to July added to momentum that was already building. July 2024 recorded CN¥ 3.33 billion in monthly revenue, up from CN¥ 2.84 billion in July 2023 and the largest monthly figure in the dataset. Volume followed the same course, with 95.6 million units sold in July 2024 against 71.1 million in July 2023, a rise of 34.5%.
The gap between revenue growth of 14.2% for the full period and the steeper volume gains in July points to two dynamics that reinforce each other. Marketplaces have expanded their logistics, which makes faster delivery of ambient and refrigerated beverages possible and brings more buyers in, and consumers are gradually trading up within some categories. We believe brands that plan around this combination of more buyers overall, paying more per unit in some segments, are best placed to decide where to put product and pricing investment.
Beverage market revenue accelerates through summer 2024, driven by consistent volume gains
Health-Oriented Sub-Categories Grow Fastest#
Growth across the thirteen beverage sub-categories in the dataset is polarised, and the dividing line runs between health-oriented formats, which grew fastest, and older categories, which stalled. Tea beverages more than doubled with growth of 117.5% YoY, expanding from CN¥ 1.23 billion to CN¥ 2.68 billion. Electrolyte drinks posted the highest percentage gain in the dataset at 132.7%, reaching CN¥ 74.8 million on a small base, as everyday hydration and sports recovery won more attention from consumers. Herbal tea (凉茶) grew 77.9%, which reflects the growing acceptance of traditional Chinese wellness beverages sold online.
The largest sub-category by revenue, drinking water, grew 36.0% YoY to CN¥ 4.76 billion, which shows that expanded marketplace logistics are benefiting ambient staples as well. Carbonated beverages ranked third at CN¥ 2.57 billion, up 43.8%, with craft and premium imported variants pushing prices in the category upwards.
Revenue was lower than a year earlier in three sub-categories across the marketplaces covered, by 8.5% for plant-based beverages, 11.3% for sparkling water and 1.5% for sour plum drink. The reversal in sparkling water stands out. After very fast growth in 2021 and 2022 the category is settling towards a more stable long-term level as its novelty fades and its positioning has not set it far enough apart from standard water. We believe tea beverages and electrolyte drinks offer the strongest growth opportunities, while sparkling water and plant-based drinks need a new reason to buy if demand is to recover.
Content-Led Marketplaces and Tea Launches#
The most consequential channel development in H1 2024 was the part content-led marketplaces played in tea beverages. On a leading content-led marketplace, tea beverage revenue grew from CN¥ 53 million to CN¥ 755 million in one year, a fourteenfold increase. Five of the ten best-selling tea products in H1 2024 were sold mainly or only on content-led marketplaces.
We read this as content-led commerce finding the use it suits best, which is the launch of new products and the creation of new categories for novel, health-oriented beverages. Staples and bulk purchases depend more on the logistics, grocery-style delivery and flagship-store infrastructure that search-led marketplaces have built for ambient and refrigerated beverages.
Brand Strategies in Tea Beverages#
Sales of tea beverages are concentrated among large, established brands with loyal buyers, deep logistics relationships and large marketing budgets, so a new brand that competes with them head-on faces a difficult task. The established names include Nongfu Spring (农夫山泉), Master Kong (康师傅), Suntory (三得利), Uni-President (统一) and Vita, and each has taken a different route.
Nongfu Spring has built its tea business on its Oriental Leaves (东方树叶) range of premium teas with no sugar and no additives, which has become the reference point for tea positioned on health and suits the demand for premium refreshment that summer weather brings.
Master Kong's approach to distribution is instructive. It sells a large part of its tea beverages through a quick-delivery grocery channel, which captures the intent to buy chilled beverages at the moment consumers plan what they will consume, and not while they browse. We believe this shows that distribution can matter more than product differentiation in a category where consumers already know the brands well. Suntory, for its part, relies on the premium signal of a Japanese brand in the CN¥ 60–80 price tier.
For challenger brands, a concentrated market still rewards thinking about channels first. Product discovery on content-led marketplaces remains effective for brands with novel ingredients or distinctive health claims. The CN¥ 40–60 functional tier is underserved relative to the growth flowing into it, which makes it the clearest gap for new entrants with a convincing health story.
Strategic Implications: Where Brand Investment Should Flow#
Five strategic conclusions follow from the H1 2024 data.
First, build volume on search-led marketplaces and use content-led marketplaces for launches. Search-led marketplaces have expanded the logistics that beverage distribution depends on, which makes them the foundation for a beverage brand. Investment in content-led marketplaces earns most on new products with the potential to spread quickly, and less on sustaining broad category sales.
Second, tea beverages are the most important sub-category opportunity of 2024. With growth of 117.5% and CN¥ 2.68 billion in revenue in H1 alone, the category is on course for full-year online sales above CN¥ 4.5 billion. Brands without a tea beverage product are missing one of the fastest-growing parts of the online beverage market.
Third, price the product in the CN¥ 20–40 tier with a health credential. The CN¥ 0–20 and CN¥ 20–40 price tiers each grew more than 200% YoY within tea beverages. Claims of no sugar, zero calories and food-medicine homology are what set the successful products apart, more than price alone.
Fourth, treat quick-commerce channels as a lasting opportunity and not as a promotional tactic. Master Kong's experience in quick-delivery grocery shows that changing the channel mix can produce growth that marketing spend alone cannot. Brands with well-known names that want to regain momentum on the shelf should consider quick-commerce placement as a main route to growth.
Fifth, watch ginseng and sea buckthorn as the next wave. These food-medicine homology (药食同源) ingredients are appearing at the edge of the concept map, at an early stage but on the kind of course that has preceded fast growth in the past. We believe brands that invest in product development now will be early to market if the trend reaches mass adoption.
Key Takeaways#
- China's online beverage market reached CN¥ 17.51 billion in H1 2024, up 14.2% YoY, with the summer peak from May to July producing the strongest gains on 2023.
- Tea beverages, up 117.5% YoY to CN¥ 2.68 billion, and electrolyte drinks, up 132.7%, are the fastest-growing sub-categories, while sparkling water fell 11.3% and plant-based beverages 8.5% across the marketplaces covered.
- On a leading content-led marketplace, tea beverage revenue grew fourteenfold to CN¥ 755 million, and content-led marketplaces have become an important channel for tea launches.
- Tea beverage sales are concentrated among large, established brands, and Master Kong's use of quick-delivery grocery shows that channel strategy can be as effective a route to growth as product innovation.
- For challengers, the opening lies in launching on content-led marketplaces, pricing in the CN¥ 20–40 tier with a no-sugar or food-medicine homology claim, and scaling up on search-led marketplaces once demand is proven.
About the Data#
This analysis is based on Moojing Market Intelligence data covering leading Chinese e-commerce marketplaces. Data covers January–July 2024 with year-on-year comparisons to the equivalent period in 2023.
Download the Full Report#
This content adheres to Moojing's editorial standards .
Frequently Asked Questions
CN¥ 17.51 billion, up 14.2% year on year, its strongest first half on record, with growth accelerating rather than front-loaded. July 2024 recorded CN¥ 3.33 billion in monthly revenue against CN¥ 2.84 billion a year earlier, and volume moved from 71.1 million to 95.6 million units (+34.5%). Volume outpacing revenue that sharply points to two reinforcing dynamics: expanding platform logistics enabling faster delivery of ambient and refrigerated beverages, which brings more buyers in, and gradual premiumisation within select segments. More buyers overall, paying more per unit in specific places, is the shape to plan against.
Health-oriented formats, decisively. Tea beverages more than doubled at +117.5%, from CN¥ 1.23 billion to CN¥ 2.68 billion. Electrolyte drinks posted the highest rate in the dataset at +132.7% to CN¥ 74.8 million, on a small base, as everyday hydration and sports-recovery narratives gained ground. Herbal tea added +77.9% as traditional Chinese wellness beverages mainstreamed. The scale categories grew solidly too, with drinking water up 36.0% to CN¥ 4.76 billion and carbonated drinks up 43.8% to CN¥ 2.57 billion. Three moved backwards: plant-based beverages -8.5%, sparkling water -11.3% and sour plum drink -1.5%. Sparkling water is the notable reversal, settling toward equilibrium after its 2021-2022 surge because its positioning never sufficiently differentiated from standard water.
Consolidated at the top and open underneath. Sales of the CN¥ 2.68 billion tea beverage category are concentrated among a handful of large brands, so a head-on fight against incumbents with established loyalty, deep logistics relationships and large budgets is structurally daunting. But the entry route is visible. Content-led discovery remains powerful for novel ingredients and distinctive health claims, and several of the highest-selling tea products in the half were sold mainly or only through content-led channels. And the CN¥ 40-60 functional tier is underserved relative to the growth flowing into it, with the CN¥ 0-20 and CN¥ 20-40 tiers each growing over 200% within tea.
That distribution architecture can outperform product differentiation when brand recognition is already high. Master Kong routed much of its tea business through a quick-delivery grocery channel, capturing chilled-beverage purchase intent at the moment of consumption planning rather than during passive browsing, while Nongfu Spring built its tea business on premium no-sugar positioning. Of the two routes, the quick-commerce one is the more replicable for an established brand whose name consumers already know.


