China Tea Beverages +117.5%: The Content-Commerce Disruption
 By Jotham Lim
7 min read
Newer data: Beverage Efficacy Claims Grew 26.6% in China in H1 2026
Executive Summary#
China's online tea beverage market more than doubled in H1 2024, reaching CN¥ 2.68 billion, a growth of 117.5% YoY. The growth was driven by the rise of content-led commerce as a channel for the category and by sugar-free, health-credentialed products in the mid-price tiers. At CN¥ 589 million in July 2024 alone, the category showed no sign of levelling off. We believe the emergence of milk tea (+4,095.1% YoY) and fruit tea (+664.8% YoY) points to where its next stage of growth may come from.
The Growth Trajectory: A Category That More Than Doubled in One Year#
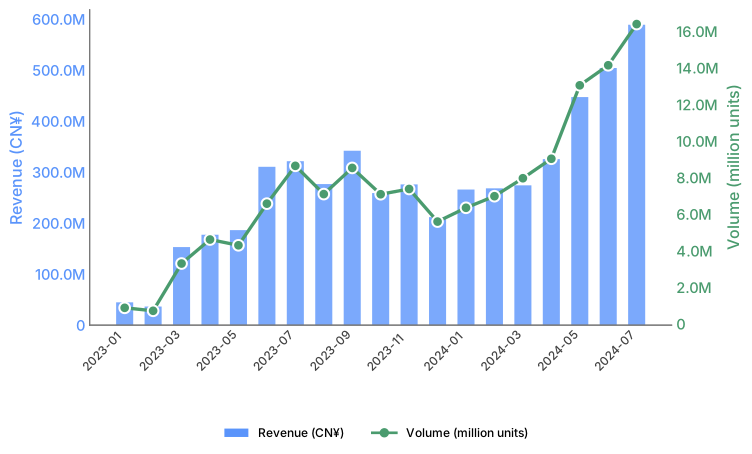
Tea beverages had the highest growth rate of any beverage sub-category in the dataset in H1 2024, and the monthly figures show a curve that kept rising, with no single month accounting for the result. Revenue for January–July 2024 reached CN¥ 2.68 billion, up from CN¥ 1.23 billion in the same period of 2023, and July 2024 alone generated CN¥ 589 million, against CN¥ 322 million in July 2023.
The growth comes from a higher baseline, since the average monthly revenue for tea beverages was CN¥ 382 million in H1 2024 against CN¥ 175 million in H1 2023, an increase of 118%. Revenue climbed from CN¥ 266 million in January to CN¥ 589 million by July as summer demand added to a level that was already high. Volume followed revenue, with 16.4 million units sold in July 2024 against 8.6 million in July 2023, a 90% increase that shows new consumers entering the category.
Tea beverage revenue reaches CN¥ 589M in July 2024
Content-Led Commerce and the Tea Category#
Content-led commerce grew quickly as a channel for tea beverages over the year. The product suits the way that channel sells, since a livestream that shows the packaging, the flavour credentials and the sugar-free formulation of a new oolong can turn a passive viewer into a buyer within seconds. Several of the best-selling tea products of the half were sold mainly through content-led channels, where brands launched them with strategies built for the format.
Price Tier Dynamics: Affordability and Health Grow Together#
Tea beverage consumers in H1 2024 bought mainly in the CN¥ 0–40 price range, and both tiers in that range more than tripled in revenue, with the CN¥ 0–20 bracket growing 226.7% YoY and the CN¥ 20–40 bracket 202.5% YoY. Together these two tiers account for approximately 65% of the category by unit count.
We believe the main source of growth is accessible, health-led products, with premium positioning playing a smaller part. The CN¥ 40–60 tier grew 130.7%, which shows real demand in the lower premium range for multi-packs and specialty formats. The CN¥ 60–80 tier grew a more modest 39.7%, which suggests that brand loyalty holds at that level while most of the category's growth goes to the cheaper tiers. The CN¥ 100+ tier nearly tripled (+175.9%) from a small base, which points to a niche of connoisseurs buying specialty sets and premium imports.
Flavour and Ingredient Innovation: Lemon at the Core, New Tea Bases at the Edges#
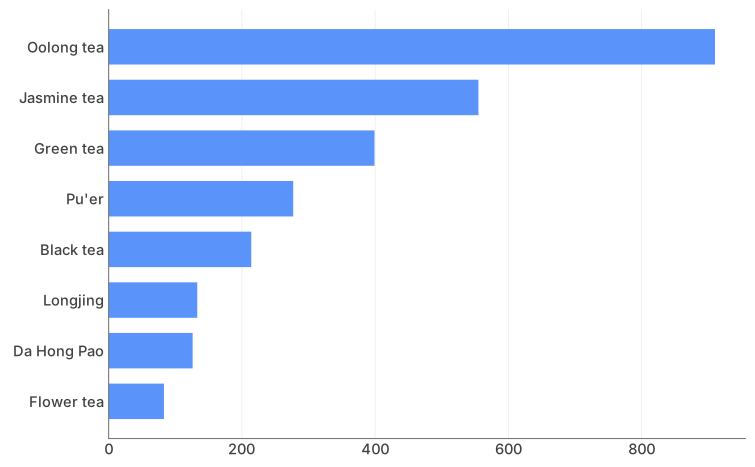
Oolong tea and jasmine tea are the basis of China's online pure tea products, together accounting for nearly half of all pure tea SKU titles listed in H1 2024, with green tea and pu'er making up the rest of the established core. The newer signals appear in the smaller tea types.
Longjing (龙井, dragon well green tea) is one of them, since it has long been associated with premium loose-leaf teas priced at hundreds of yuan, and its appearance in RTD formats, typically below CN¥ 30, brings the flavour's cultural appeal to accessible price points. Da Hong Pao (大红袍) follows the same approach with 126 SKUs, and we believe this shows that the story of a premium tea base can move into RTD formats without losing its appeal.
Oolong and jasmine dominate pure tea product SKU counts; Longjing gains ground
Brand Strategies: Health Positioning and Premium Signals#
Sales in the tea beverage category are concentrated among a small group of established brands, which compete from different positions. Nongfu Spring (农夫山泉) has built its tea business on its Oriental Leaves (东方树叶) franchise, a range of no-sugar, no-additive teas that has become closely associated with the health-first segment. Suntory (三得利) draws on its image as a Japanese brand to support higher per-unit prices in the CN¥ 60–80+ tier.
Master Kong Case Study: Quick Commerce Through Taobao Grocery#
Master Kong (康师傅) offers a useful case of channel strategy in H1 2024, because its iced black tea and standard oolong products have existed for decades and what changed was the way they reached buyers.
Master Kong sells its tea beverages through Taobao Grocery (淘宝买菜), an instant-delivery service that delivers beverages within hours. The channel suits the category for three reasons. Its buyers tend to order several items at once, it serves demand for ambient and chilled drinks that are consumed shortly after delivery, and its grocery interface shows products to shoppers at the moment they intend to buy. By price, Master Kong's tea range sits mainly in the CN¥ 20–40 tier, which is consistent with the brand's traditional value positioning.
We believe the case shows that distribution can matter as much as product differentiation for the wider market, because quick-commerce channels gave an established brand a new way to reach buyers, and did so faster and at lower cost than above-the-line advertising could have done.
The Next Wave: Milk Tea and Fruit Tea Are Small but Growing Fast#
Flavoured tea accounted for 84.5% of the tea beverage market in H1 2024, with lemon iced tea, peach green tea and similar formats with added flavours forming its core, while the smaller sub-categories show the fastest growth.
Milk tea (奶茶) grew 4,095.1% YoY from a small base, as RTD formats entered channels previously served by fresh-made bubble tea shops. As consumers look for convenient versions of their café favourites, online RTD milk tea is creating a new purchase occasion. Fruit tea (果汁茶) grew 664.8%, while pure tea (纯茶), the no-additive segment favoured by health-minded buyers, grew 510.5%.
We believe the tea beverage category is at an early stage of dividing into distinct sub-segments. Brands that act on these signals by building RTD milk tea and fruit tea products, launched through content-led commerce and priced around CN¥ 20–40, are well placed to benefit from the category's next wave of growth.
Key Takeaways#
- China's online tea beverage market reached CN¥ 2.68 billion in H1 2024, up 117.5% YoY, with July 2024 alone generating CN¥ 589 million.
- Content-led commerce became an important channel for tea beverage launches, because livestreams suit the way tea products are presented and sold.
- The CN¥ 0–20 and CN¥ 20–40 price tiers each grew over 200% YoY, which shows that accessible, health-credentialed products are drawing the widest range of buyers.
- Master Kong's use of Taobao Grocery's quick delivery shows that a channel strategy can renew an established brand without a change of product.
- Milk tea (+4,095.1%) and fruit tea (+664.8%) are still small sub-segments, but their growth points to the next shift in how Chinese consumers buy tea beverages online.
About the Data#
This analysis is based on Moojing Market Intelligence data covering China's major e-commerce platforms including Tmall (天猫), JD.com (京东), Taobao (淘宝), and Douyin (抖音). Data covers January–July 2024 with year-on-year comparisons to the equivalent period in 2023.
Download the Full Report#
More from This Report#
This content adheres to Moojing's editorial standards .
Frequently Asked Questions
It more than doubled, reaching CN¥ 2.68 billion in H1 2024 against CN¥ 1.23 billion a year earlier, a rise of 117.5% and the highest of any beverage sub-category in the dataset. The growth came from a higher baseline, with no single month accounting for it. Average monthly revenue went from CN¥ 175 million to CN¥ 382 million, an increase of 118%, and revenue climbed from CN¥ 266 million in January to CN¥ 589 million by July. Volume shows new buyers entering the category, with 16.4 million units sold in July 2024 against 8.6 million a year earlier, an increase of 90%.
The product suits the way that channel sells. A livestream that shows the packaging, the flavour credentials and a sugar-free formulation can turn a passive viewer into a buyer within seconds, which is much harder to do for a bulk order of water. Several of the half's best-selling tea products were sold mainly through content-led channels. The category's growth of 117.5% is measured across all the marketplaces in the dataset, so content-led commerce added to demand that was rising across the category as a whole.
The accessible tiers grew fastest. The CN¥ 0-20 bracket grew 226.7% and CN¥ 20-40 grew 202.5%, and together they account for roughly 65% of the category by unit count. Above them, CN¥ 40-60 grew 130.7% on multi-pack and specialty formats, while CN¥ 60-80 grew only 39.7%, which suggests that brand loyalty holds at that level while most of the growth goes to the cheaper tiers. The CN¥ 100+ tier nearly tripled, at 175.9%, from a small base, a niche of connoisseurs buying specialty sets and premium imports. We believe accessible, health-led products drive the category's growth more than premium positioning does.
The sub-segments that are still small enough to enter. Flavoured tea held 84.5% of the market in H1 2024, with lemon iced tea, peach green tea and similar formats forming its core, but the fastest growth was in the smaller sub-categories. Milk tea grew 4,095.1% from a small base as ready-to-drink formats entered channels previously served by fresh-made bubble tea shops, creating a new purchase occasion. Fruit tea grew 664.8% and pure no-additive tea 510.5%. Oolong and jasmine account for nearly half of pure tea listings. Meanwhile, the story of a premium tea base is moving into ready-to-drink formats at accessible prices, which gives brands a route into the category without competing on the established flavours.


