Premium Shift Reshapes China's CN¥ 104B Sportswear Market
 By Quan Wenjun
4 min read
Newer data: China's Online Sportswear Sales Hit CN¥ 168.3B in 2025
Executive Summary#
China's online sports footwear and apparel market generated CN¥ 104.4 billion in MAT2023, a fall of 4.25% year-on-year (YoY) that was much smaller than the falls in women's clothing (14.0%) and men's clothing (11.5%)[1]. Within the category, consumers are trading up to higher price segments, and on a leading marketplace the CN¥ 600-800 range grew 25.1% to CN¥ 13.3 billion while the budget CN¥ 0-200 segment came under pressure. This analysis looks at the move toward premium products, at how the category's sales divide between footwear and apparel and at what the pricing shift means for brands selling on two of China's largest marketplaces.
Download Full Report#
Get the complete analysis with brand-level data, consumer sentiment insights, and competitive benchmarking across all major sportswear categories.
Download the Full Q2 2023 Sports Footwear & Apparel Whitepaper →
Sportswear Held Up Better Than the Wider Apparel Market#
China's sportswear market held up far better than the wider online apparel sector in MAT2023. Its fall of 4.25% compares with falls of 14.0% in women's clothing and 11.5% in men's clothing, which reflects lasting consumer demand for athletic and casual wear. We believe health consciousness and the growing popularity of outdoor activities continue to support it.
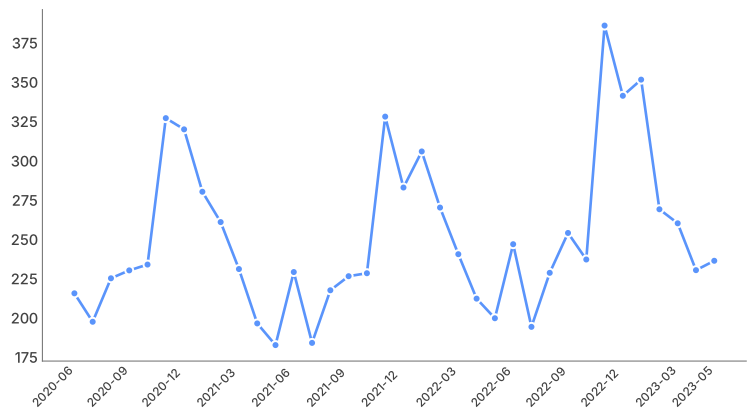
Total sales volume reached 380.2 million units across the marketplaces covered. Monthly data shows strong seasonality driven by the major promotional events, with November's Double 11 festival and June's 618 festival producing peaks year after year.
Consumers Trade Up to Higher Price Tiers#
On a leading marketplace, the CN¥ 600-800 segment grew from CN¥ 10.6 billion in MAT2022 to CN¥ 13.3 billion in MAT2023, an increase of 25.1%. The budget CN¥ 0-200 segment came under pressure over the same period, and the CN¥ 200-400 segment came under less pressure than the budget tier. The premium segment (CN¥ 800-1000), by contrast, grew 32.0%, from CN¥ 5.4 billion to CN¥ 7.1 billion, which shows that consumers are trading up within the category and are not leaving it.
We believe the move toward higher price tiers has several drivers:
- Rising consumer expectations for technical performance and differentiated design
- Strong brand investment in the mid-high price tier, particularly from Nike and Fila
- Aspiration, driven by social media, for retro-casual and fashion-forward athletic footwear
The same shift toward higher price tiers appears on the other marketplace in the dataset, which suggests that the trend comes from consumers and is not specific to one marketplace.
Brand Positioning Across Price Tiers#
Brands position themselves in different parts of the price range. Below CN¥ 400, the domestic brands Anta (安踏) and Li Ning (李宁) compete on value for money, while Nike has invested strongly in the mid-high price tiers. Fila concentrates on the CN¥ 400-800 range, where its retro-casual aesthetic appeals to consumers willing to pay a premium for fashion-forward athletic wear.
Footwear Accounts for Most Sportswear Sales#
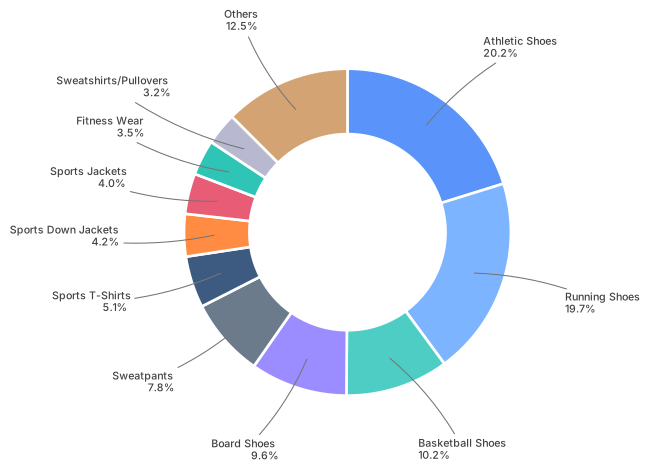
Footwear accounts for 67.1% of sportswear sales on a leading marketplace, and athletic shoes and running shoes together make up nearly 40% of its sportswear sales, which shows how central footwear is to the market. Average prices settled at approximately CN¥ 230 by May 2023, and sports shoes had the greatest influence on average prices across the market.
Footwear accounts for two-thirds of sportswear sales on a leading marketplace, led by athletic and running shoes
Average prices fluctuate seasonally around CN¥ 230 on a leading marketplace
Key Takeaways#
- China's online sportswear market generated CN¥ 104.4 billion in MAT2023, and its fall of 4.25% YoY was much smaller than the fall of 14.0% in women's clothing
- On a leading marketplace, the CN¥ 600-800 price segment grew 25.1% YoY to CN¥ 13.3 billion as consumers traded up from the budget tiers
- Footwear accounts for 67.1% of sportswear sales on a leading marketplace
- Brands position themselves across the price range, with domestic brands competing on value for money below CN¥ 400 and Nike and Fila investing in the mid-high tiers
- Average selling prices settled at approximately CN¥ 230, while beneath that average consumers moved toward higher-value purchases
## About the Data
This analysis draws on Moojing Market Intelligence data covering the MAT2023 period (June 2022 to May 2023). Moojing analyses brand and category performance on two of China's largest marketplaces. For full methodology and additional insights, see the complete Sports Footwear and Apparel whitepaper.
This content adheres to Moojing's editorial standards .


