China Disposable Products Q3 2024: Pandemic to Lifestyle
 By Jotham Lim
6 min read
Executive Summary#
China's online disposable consumer products market on two leading Chinese marketplaces generated CN¥ 6.16 billion in January through August 2024, and while sales as a whole came under pressure, the mix of products beneath the total changed considerably. Protective equipment, the largest part of the category at the pandemic peak of 2022, fell from 38% to 23% of revenue share. Personal care disposables grew to 37% (+6pp) and clothing disposables to 34% (+8pp) in its place, on the strength of underwear, socks, face towels and travel hygiene products. We believe the market has moved from purchases made out of necessity in a crisis to purchases made for convenience in everyday life. In our view, the most promising themes for investment in 2024 were travel and personal hygiene at accessible price points.
Market Overview: CN¥ 6.16 Billion After the Pandemic#
China's disposable consumer products market was extremely volatile between 2022 and 2024. At the pandemic peak in November and December 2022, disposable face masks alone accounted for 74.5% of category revenue. Demand returned to normal as COVID restrictions were lifted in early 2023, and the market settled into a monthly range of CN¥ 500 million to CN¥ 1 billion.
The January through August 2024 period reflects this normal baseline. We believe the pressure on sales over the year came mainly from the continued unwinding of pandemic-era purchases of protective equipment, with underlying consumer demand for convenient disposable goods holding up. By mid-2024, monthly revenue had stabilised at approximately CN¥ 750 million to CN¥ 850 million, a level that reflects everyday use of the products by consumers.
The Category Shift from Protection to Personal Care#
The most significant structural change in 2024 is the rebalancing of product categories. The revenue share of protective equipment, mostly disposable face masks, fell from 38% in Jan-Aug 2023 to 23% in 2024, a change of 15 percentage points as concern about the pandemic faded. Personal care products (face towels, towels, underwear) grew from 31% to 37% of revenue, and clothing disposables (underwear, socks) from 26% to 34%.
We believe more is at work here than simple substitution. The categories gaining share are those that fit wider consumer trends: the recovery of domestic travel, which drives demand for portable hygiene products, rising personal care standards among young urban women, and a "single-use lifestyle" in which convenience matters more than the routines of laundry and upkeep.
Who Is Buying: Young Women and Travel#
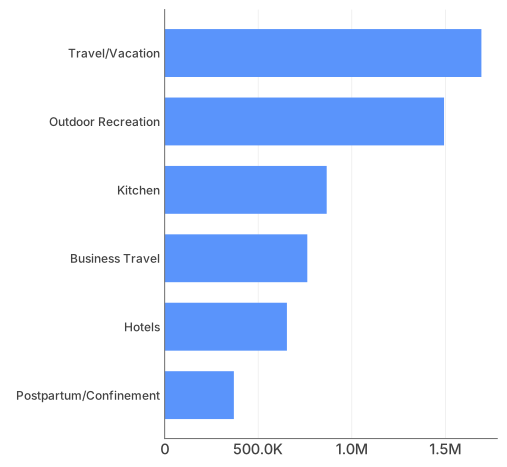
Women aged 21-30 are the core consumers, and the 21-30 cohort's share of social media discussion of the category rose by 3.1 percentage points year-on-year to 33.3%. Travel and vacation contexts account for the largest share of demand, with 1.69 million social media mentions, followed by outdoor recreation at 1.49 million. Together with business travel and hotel stays, scenarios linked to travel account for more than 60% of all scenario-specific discussion.
One content platform carries 70.1% of social media conversation about disposable products, which makes it the main platform for brand visibility. Overall social media engagement with the category fell 44.4% year-on-year, which we believe shows that conventional product-focused content is attracting less attention. Brands therefore need content built around usage scenarios, such as travel packing tutorials, hotel hygiene tips and content about everyday life, to keep consumers engaged.
Travel and vacation scenarios dominate disposable product demand with 1.69 million social media mentions
Disposable Underwear: Growth to CN¥ 1.16 Billion#
Disposable underwear grew against the trend of the wider category, with CN¥ 1.16 billion in Jan-Aug 2024 revenue, up 8.1% year-on-year. Volume grew faster still, and July 2024 recorded 5.07 million units, 2.5 times the July 2022 level. Social media discussion more than doubled to over 1 million posts, growing 117.3% YoY, and peaked in July, when a viral debate about underwear hygiene standards and a travel marketing campaign by MINISO drew exceptional engagement.
Concentration among brands is low and the market moves quickly. Brands serve clearly different price segments: Emxee (嫚熙) targets premium maternity buyers, Badi Gao (巴迪高) the mid-range, and Qihaixiu (七海秋) the budget segment, which we believe is where most of the growth in volume comes from.
What Consumers Want: Sizing, Comfort and Honest Materials#
Analysis of consumer feedback shows that sizing and fit issues account for 33.2% of all negative feedback, the largest single pain point by a wide margin, with common complaints such as "runs small", "too tight" and "no elasticity". Thickness consistency (13.0%) and material truthfulness (11.7%) are the next largest concerns, and consumers often report that products marketed as "pure cotton" feel like synthetic non-woven fabric.
On the positive side, breathability is the most valued comfort attribute (12.6% of comfort discussions), followed by softness and gentleness on the skin. Mentions of "comfortable" grew 157.9% year-on-year, which we believe shows that consumers increasingly expect disposable underwear to meet the standards of regular underwear. Brands that invest in better elastic, a choice of thicknesses and verified material claims stand to gain a disproportionate share of sales.
Strategic Takeaways#
- The disposable products market has moved from pandemic protection to everyday convenience, and by mid-2024 the monthly revenue baseline of CN¥ 750-850M was the true size of the market.
- Travel recovery is the main driver of demand, so brands should prioritise distribution partnerships with travel and hospitality platforms and invest in portable, individually wrapped packaging.
- Disposable underwear is the category's strongest source of growth. Revenue growth of 8.1% and growth of 117.3% in social media discussion, in a market where concentration among brands is low, leave considerable room for focused brand building.
- Volume growth is concentrated in the budget segment below CN¥ 20, which gained 15pp of volume share in two years, although the mid-premium CN¥ 40-50 tier remains viable for brands that can offer verifiable differences in quality.
- Better sizing is the product improvement with the highest return, since 33.2% of negative feedback concerns fit, and better elastic construction and wider size ranges are the most direct route to better ratings and repeat purchases.
About the Data#
This analysis is based on Moojing Market Intelligence data from two leading Chinese marketplaces, together with social media analysis across major Chinese social platforms. Data covers January 2022 through August 2024.
Download the Full Report#
This content adheres to Moojing's editorial standards .


